• Skip to primary navigation
  • Skip to main content
  • Skip to primary sidebar
  • Skip to footer
location iconSuite 503, 5/F, St. George's Building, 2 Ice House Street, Central, Hong Kongphone-icon +852 2868 0696 linkedintwitterfacebook
OLN IP Services
close-btn
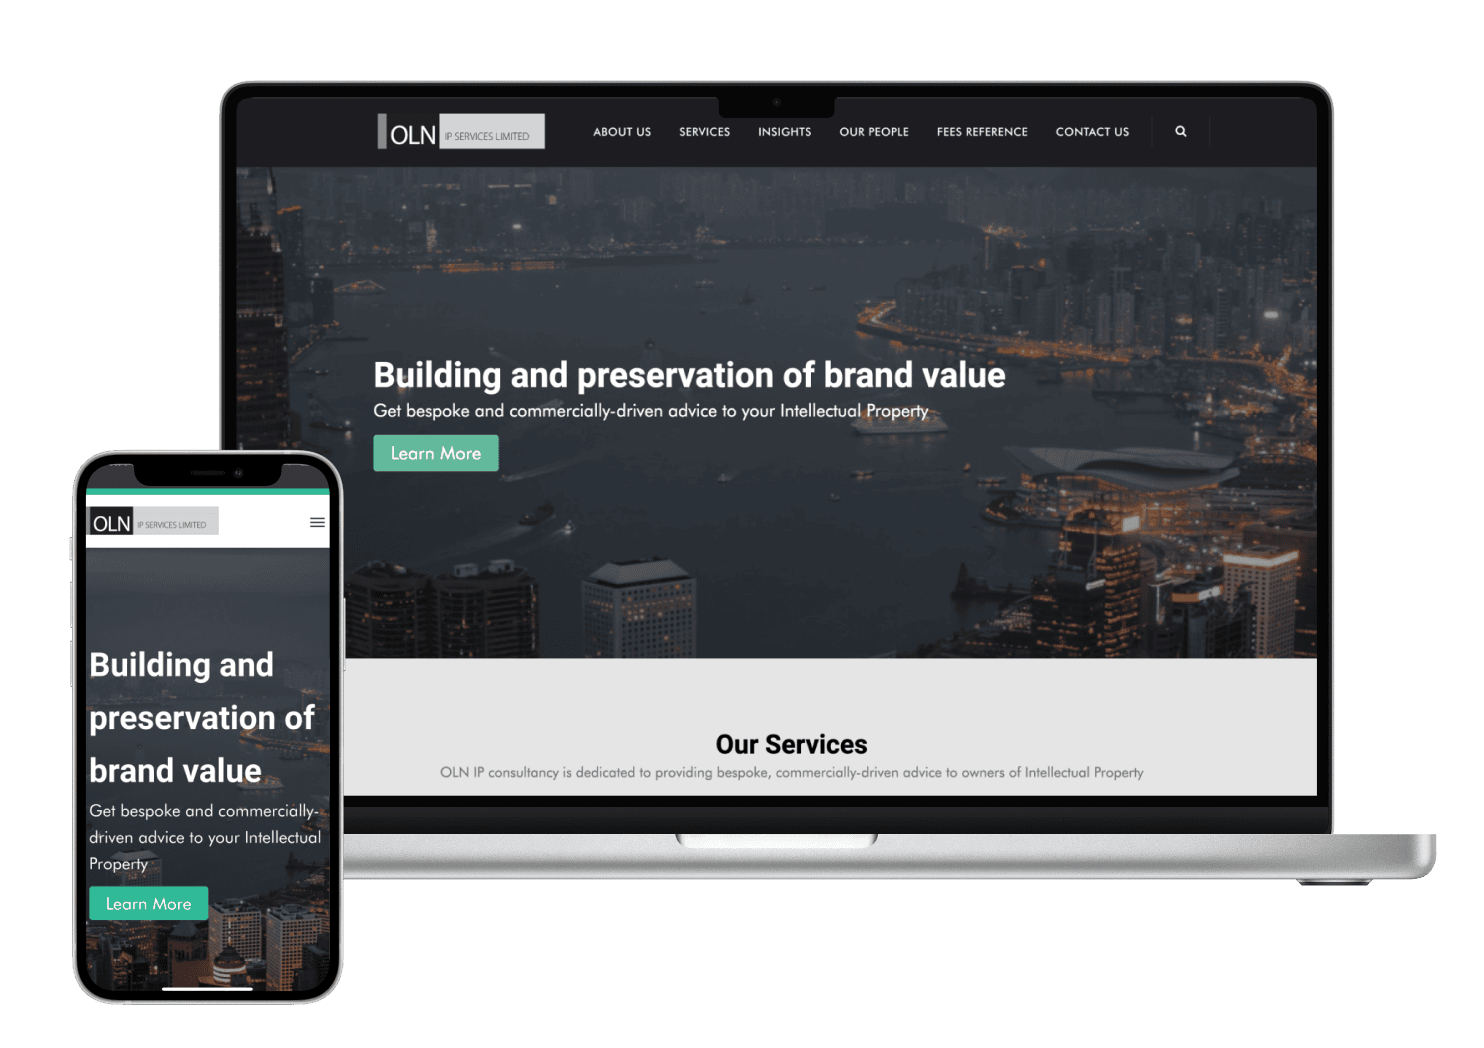
OLN IP Services
Get bespoke and commercially-driven advice to your Intellectual Property
Learn More
OLN IP Services
OLN Online
close-btn
OLN Online
Powered by Oldham, Li & Nie, the law firm of choice for Hong Kong’s vibrant startup and SME community, OLN Online is a forward-looking and seamless addition to traditional legal services – a true disruptor.
Learn More
OLN IP Services
OLN CS
close-btn
OLN CS
OLN was established in 1987 by Gordon Oldham with the goal of providing both quality legal advice and practical legal solutions to the business community.
Learn More
OLN CS Services
  • 日本語
    • ENG
    • 简
    • 繁
    • FR
    • IT
Oldham, Li & Nie
OLN IP Services
close-btn
OLN IP Services
Get bespoke and commercially-driven advice to your Intellectual Property
Learn More
OLN IP Services
OLN Online
OLN CS
close-btn
OLN Online
Powered by Oldham, Li & Nie, the law firm of choice for Hong Kong’s vibrant startup and SME community, OLN Online is a forward-looking and seamless addition to traditional legal services – a true disruptor.
Learn More
OLN IP Services
  • について
        • 受賞歴・ランキング
        • 企業の社会的責任
  • 業務内容
        • Canadian Notarization Services
        • チャイナ法務
        • 人事労務・就労系ビザ関連法
        • 破産法
        • 人身傷害に関する法
        • 税務
        • 企業法務
        • 家族法
        • 保険法
        • プライベートクライアント
        • 商取引上の不正・資産回復
        • フランス法務
        • 知的財産法
        • 金融サービス・許認可
        • 紛争解決
        • ファンドプラクティス
        • 公証業務
        • ジャパニーズ・プラクティス
        • スタートアップ
        • Canadian Notarization Services
        • チャイナ法務
        • 家族法
        • 金融サービス・許認可
        • 人事労務・就労系ビザ関連法
        • 保険法
        • 紛争解決
        • 破産法
        • プライベートクライアント
        • ファンドプラクティス
        • 人身傷害に関する法
        • 商取引上の不正・資産回復
        • 公証業務
        • 税務
        • フランス法務
        • ジャパニーズ・プラクティス
        • 企業法務
        • 知的財産法
        • スタートアップ
        • Italian Practice
  • 弁護士紹介
  • インサイト
  • 事業拠点

Suite 503, St. George's Building,
2 Ice House Street, Central, Hong Kong

Tel. +852 2868 0696 | Send Email
linkedin twitter facebook
OLN Blue

OLN Law

  • Block Content Examples
  • Client Information & Registration
  • Contact Us
  • Cookie Policy (EU)
  • Globalaw
  • Oldham, Li & Nie
  • OLNと地域社会
  • OLNポッドキャスト
  • Our People
  • Privacy Policy
  • Review
  • Reviews
  • Standard Terms of Engagement
  • 事業拠点
  • 受賞歴・ランキング
  • 当事務所について
  • 当事務所の歴史
    • OLN | おける企業としての社会的責任
    • 受賞歴・ランキング
  • 採用を希望する方へ
  • 業務内容
  • 評判
  • について
        • 受賞歴・ランキング
        • 企業の社会的責任
  • 業務内容
        • Canadian Notarization Services
        • チャイナ法務
        • 人事労務・就労系ビザ関連法
        • 破産法
        • 人身傷害に関する法
        • 税務
        • 企業法務
        • 家族法
        • 保険法
        • プライベートクライアント
        • 商取引上の不正・資産回復
        • フランス法務
        • 知的財産法
        • 金融サービス・許認可
        • 紛争解決
        • ファンドプラクティス
        • 公証業務
        • ジャパニーズ・プラクティス
        • スタートアップ
        • Canadian Notarization Services
        • チャイナ法務
        • 家族法
        • 金融サービス・許認可
        • 人事労務・就労系ビザ関連法
        • 保険法
        • 紛争解決
        • 破産法
        • プライベートクライアント
        • ファンドプラクティス
        • 人身傷害に関する法
        • 商取引上の不正・資産回復
        • 公証業務
        • 税務
        • フランス法務
        • ジャパニーズ・プラクティス
        • 企業法務
        • 知的財産法
        • スタートアップ
        • Italian Practice
  • 弁護士紹介
  • インサイト
  • 事業拠点

Insight from the Recent CFA decision in Commissioner of Inland Revenue v Poon Cho Ming, John – Whether Benefits Received on Termination of Employment are Taxable or Not

Test Blog

Insight from the Recent CFA decision in Commissioner of Inland Revenue v Poon Cho Ming, John – Whether Benefits Received on Termination of Employment are Taxable or Not

2021年11月30日 by OLN Marketing

Employee termination is not uncommon during economic downturn or group restructuring. The termination payments or the compensation packages, especially for top executives or senior employees, often consist of many components such as salaries, gratuities, discretionary bonuses, golden handshakes, settlement sum for the employment dispute. Given the diversified nature of the compensation components, it might not be easy to identify which part of entire package is taxable and which is not under the definition of section 8(1) of the Inland Revenue Ordinance, Cap. 112 (“IRO”).

As a starting point, the IRO provides that only income earned in the course of employment is chargeable to salaries tax. It is however not always easy to determine which compensation component has direct corelation to the employment and which is not. The precedent case, Fuchs v Commissioner of Inland Revenue [2011] 14 HKCFAR 74, offers some guidance on this issue. The Court ruled in Fuchs that what an employee received in satisfaction of his rights under his contract of service was taxable, while what he received in abrogation of his rights under the contract was not taxable.

The Court of Final Appeal has reaffirmed such position in its recent decision in Commissioner of Inland Revenue v Poon Cho Ming, John [2019] HKCFA 38 whereby it was held that rewards for past services and inducements to enter into employment and providing future services are chargeable under the said provision, whereas payment which were for something else were not chargeable. This article seeks to discuss the legal principles concerning the subject matter and how unnecessary dispute could be avoided.

A. Brief facts in Poon Cho-Ming case

The Respondent Taxpayer (‘Respondent’) was employed as a director of the Company pursuant to a written employment contract dated 20 October 1999 (‘Service Agreement’). In July 2008, his employment was abruptly terminated without cause. The Respondent and the Company entered into negotiations, with legal representatives on both sides, which resulted in a separation agreement dated 20 July 2008 (‘Separation Agreement’) to terminate the employment on the same day.

During the employment, the Respondent was eligible to be considered for a discretionary bonus and for the grant of unvested share options under an employee’s shares option scheme. Under the scheme, Options granted in one year would vest, provided the Respondent was still employed by the company, in annual tranches over the following 5 years.

After the termination of his employment, the Respondent received payments and benefits from the Company and were taxed by the Commissioner of Inland Revenue. The items that were in disputes are as follows.

  1. EUR500,000 provided for under the Separation Agreement, labelled as a ‘payment in lieu of a discretionary bonus’ (‘Sum D’); and
  2. the amount derived from the exercise of the Respondent’s share options which the Company agreed under the Separation Agreement to vest on an accelerated basis (‘Share Option Gain’).

The Commissioner of Inland Revenue, the Board of Review and the Court of First Instance considered and ruled that the above sums constituted income ‘from’ the Respondent’s employment and were therefore chargeable to Salaries Tax under section 8(1) of the IRO.

The Respondent appealed to the Court of Appeal which overturned the CFI’s decision. The Court of Final Appeal upheld the decision of the Court of Appeal and unanimously decided that the above sums were ‘for something else’ and were not therefore taxable under section 8(1) of the IRO.

B. The relevant legal principles

The ‘operative test’ is succinctly summarized by Ribeiro PJ in Fuchs (at para 22).

In short, the question that needs to be asked is: ‘in the light of the terms on which the taxpayer was employed and the circumstance of the termination, what, in substance not form, the sum and benefits is for?’

If the purpose or nature of the payment constitutes income from employment, the payment is taxable under s.8(1) IRO, as illustrated in the table below.

 Purpose or nature of the paymentIncome from employment
(s. 8(1) IRO)
Taxability
1‘acting as or being an employee’YesYes
2 ‘as a reward for past service’ Yes Yes
3 ‘as an inducement to enter employment or for future services’ Yes Yes
4‘for something else’NoNo
C. Application of the test to the facts of Poon Cho-Ming Case

In Poon Cho-Ming case, the IRD was of the view that both Sum D (i.e. the payment in lieu of discretionary bonus) and Share Option Gain were employment income because “discretionary bonus” was employment performance-linked and Share Option Gain was derived from employee benefit scheme. 

The Court, however, was of the view that both Sum D and Share Option Gain were not Respondent’s entitlement under the terms of the Service Agreement, nor had he any accrued rights on his termination which he could enforce at law in relation to them.

Although Sum D was described as a substitution of the discretionary bonus, the Court preferred substance over form. The Court analysed the facts and found that Sum D is, in substance, materially different from the discretionary bonus, in term of their purpose and nature. The amount of Sum D was arrived arbitrarily by way of negotiation between the Respondent and the CEO of the company, without reference to the performance of the Respondent and other considerations or procedure which would have been relevant in determining discretionary bonus in the Company.

The Court also found that the accelerated vesting of the share options under the Separation Agreement constituted a new right. With regard to the terms of the Grant Letters, the Court found that the original right was plainly not exercisable on the separation date and would have lapsed if the Respondent was no longer an employee of the Company. The new right under the Separation Agreement replaced the original right under the Service Agreement, allowing the Respondent to exercise the share options within 3 months from the separation date when he was no longer an employee of the Company.

The Court of Appeal concluded (and the CFA agreed) that the purpose of Sum D and Share Option Gain were for something else. The aforesaid benefits were found to be the consideration for the Respondent Taxpayer agreeing to:-

  1. ‘go quietly’ with a joint announcement that he had ‘resigned’ to mitigate adverse market reaction;
  2. additional post-employment covenants in the Separation Agreement which created new obligations on him; and
  3. settle or abrogate any and all claims which he might have against the Company arising from the termination of his employment.
D. Insight from Poon Cho-Ming case

The CFA’s decision in Poon Cho-Ming has reaffirmed the orthodox position as set down in precedents. However, the application of the legal principles is not a straightforward exercise. Detailed analysis of the facts in each case is required. How the termination letter or the separation agreement is crafted and the wordings therein could lead to unnecessary confusion and debate.

To avoid the hassle of litigation, the employers and/or taxpayers should involve legal representatives in the early stage of termination process. A well-structured termination package, careful drafting of agreements as well as appropriate responses to the Authorities will help reflect the true intent and nature of the termination payment and save taxpayers from unnecessary tax exposure.

Our firm has extensive experience in advising on employment-related matters and on tax advisory matters. If you have any question regarding the topic discussed above, please contact our partner Anna Chan at anna.chan@oln-law.com for further assistance.

Disclaimer: This article is for reference only. Nothing herein shall be construed as Hong Kong legal advice or any legal advice for that matter to any person. Oldham, Li & Nie shall not be held liable for any loss and/or damage incurred by any person acting as a result of the materials contained in this article.
Filed Under: カテゴリーなし, 税務, 人事労務・就労系ビザ関連法

CEDB Released a Public Consultation Paper on Updating Hong Kong’s Copyright Regime on 24 November

2021年11月26日 by OLN Marketing

The Commerce and Economic Development Bureau of the Government of Hong Kong just released on 24 November 2021 a public consultation paper on updating Hong Kong’s copyright regime. 

This is brilliant news to copyright owners and fingers crossed with the passage of the new legislation! If you may wonder the meaning behind, the current Copyright Ordinance enacted in 1997 is considered badly obsolete and can barely cope with the rapid advancements and innovations in technology. Despite the Government’s deliberation to update the legislation initiated since 2006 with public consultations conducted,  two serious attempts to amend the Ordinance (The Copyright (Amendment) Bill 2011 and The Copyright (Amendment) Bill 2014) did not succeed due to filibustering by some members asserting the view that freedom of creativity or expression could possibly be compromised under the proposed legislative provisions.

The consultation paper described the legislative proposals in the 2014 Bill to be the result of years of deliberations of the Government, Legislative Council, copyright owners, online service providers and copyright users, representing the consensus and balance of interests of different stakeholders to enhance protection for copyright in the digital environment and combat large scale online piracy – which should be materialized without further delay.  

Key legislative proposals based on the 2014 Bill

A. Communication right – introduction of technology-neutral exclusive communication right for copyright owners to communicate their works to the public through any mode of electronic transmission in line with the international practice

B. Criminal liability – criminal sanctions introduced against infringers making unauthorised communication of copyright works to the public for profit or reward and with prejudice caused to the copyright owners

C. New copyright exceptions – for the education sector, libraries, museums, archives, temporary reproduction of copyright works by OSPs, and media shifting; and new fair dealing exceptions for the purposes of parody, satire, caricature and pastiche, commenting on current events, and use of quotation to facilitate expression of opinions or discussions in the online and traditional environment

D. Safe harbour provisions – limiting OSP’s liability for copyright infringements on their service platforms caused by subscribers as an incentive for OSPs to cooperate with copyright owners to combat online piracy

E. Additional damages in civil cases – empowering the court to award additional damages according to the circumstances with additional factors to assess including the unreasonable conduct of an infringer and likelihood of widespread circulation of infringing copies

Issues inviting public views

1. Should Hong Kong continue to maintain the current exhaustive approach by setting out all copyright exceptions based on specific purposes or circumstances?

2. Should Hong Kong introduce provisions to restrict the use of contracts to exclude or limit the application of statutory copyright exceptions? (currently is non-interference approach to contractual arrangements between owners and users)

3. Should Hong Kong introduce specific provisions to govern illicit streaming devices used for accessing unauthorized contents on the Internet, including set-top boxes and Apps? (Government’s current position is not to)

4. Should Hong Kong introduce a copyright-specific judicial site blocking mechanism? (Government’s current position is not to)

Issues to be considered for future legislative amendments
  • Extension of copyright term of protection
  • Introduction of specific copyright exceptions for text and data mining
  • AI and copyright

The consultation period is 3 months from 24 November 2021. We are more than happy to convey your thoughts to the Bureau or share our thoughts on issues you may have on copyright protection or circumstances that may put you at the risk of infringing someone else’s copyright.

Filed Under: カテゴリーなし, 知的財産法

Asialaw 2026 Rankings Recognise Oldham, Li & Nie’s Practices and Partners

2026年10月22日 by OLN Marketing

Oldham, Li & Nie has again been recognised in the asialaw 2026 rankings, with recommendations across several practice areas and industry sectors. The firm’s Partners also received six individual recognitions.

Alongside these rankings, our firm has been shortlisted in two categories at the asialaw Awards 2026.

Asialaw 2026 Highly Recommended Firm
Practice Area Rankings

Asialaw 2026 recognises OLN in the following practice areas:

  • Dispute Resolution – Highly Recommended
  • Intellectual Property – Highly Recommended
  • Corporate and M&A – Recommended
  • Labour & Employment – Recommended
  • Private Client – Recommended
  • Restructuring and Insolvency – Notable
Industry Sector Recognition

The firm is also recommended in the following industry sectors:

  • Insurance – Recommended
  • Technology and Telecommunications – Recommended
Individual Lawyer Recognitions

OLN’s partners received six individual recognitions:

  • Gordon Oldham – Senior Statesman in Dispute Resolution
  • Richard Healy – Notable Practitioner in Dispute Resolution
  • Tracy Yip – Distinguished Practitioner in Corporate and M&A
  • Vera Sung – Distinguished Practitioner in Intellectual Property
  • Anna Chan – Distinguished Practitioner in Tax and Private Client
  • Victor Ng – Notable Practitioner in Corporate and M&A

We thank our clients and peers for their feedback and continued support, and congratulate our colleagues on their recognition.

For the complete rankings and individual recognitions, visit OLN’s asialaw profile.

Asialaw Awards 2026 Shortlist

OLN has also been shortlisted in two categories at the asialaw Awards 2026:

  • Oldham, Li & Nie – Hong Kong SAR Law Firm of the Year
  • Anna Chan – Hong Kong SAR Female Lawyer of the Year

View the asialaw Awards 2026 shortlist.

About Asialaw

Asialaw provides independent research and analysis of regional and domestic law firms and lawyers across Asia. Now in its 31st edition, the guide covers 20 jurisdictions and 28 practice areas and industry sectors. Its research draws on firm submissions, client feedback, peer reviews and market intelligence.

Learn more about asialaw and its research.

Filed Under: カテゴリーなし, 保険法, プライベートクライアント, 知的財産法, 破産法, 人事労務・就労系ビザ関連法, 紛争解決, 企業法務

Form 5472 Reporting: What Hong Kong-Owned U.S. Businesses Need to Know

2026年10月6日 by serena

For Hong Kong families, investing in the United States can provide access to attractive For Hong Kong businesses with U.S. subsidiaries or other U.S. entities, Form 5472 reporting may extend well beyond the company’s direct Hong Kong owner. Related companies, family members, affiliated entities, and businesses under common control can potentially come into the analysis. Understanding these relationships is an important part of meeting U.S. reporting obligations and avoiding substantial penalties.

Hong Kong companies expanding into the United States often focus first on operational matters – establishing a U.S. entity, opening bank accounts, hiring employees, entering contracts, or acquiring assets.

But establishing a U.S. presence can also create important federal tax reporting obligations.

One of these is IRS Form 5472, an information return that can apply when a U.S. corporation is at least 25% foreign owned and has reportable transactions with foreign related parties during the tax year. Certain foreign-owned U.S. disregarded entities are also subject to Form 5472 reporting under special rules. The penalties for not filing are severe. Even though the form is relatively short, the penalty is $25,000 per year, per form, for each non filing violation.

For a U.S. company owned by a Hong Kong business or individual, determining who must be reported is not always as simple as identifying the shareholder listed on the company’s records.

U.S. tax rules can extend the analysis to a much broader network of related individuals and businesses.

Form 5472 and Hong Kong Business Groups

At first glance, the ownership structure might appear straightforward: the Hong Kong parent owns the U.S. company, so the parent is the foreign owner relevant to the Form 5472 analysis.

But the reporting analysis may not end there.

If the Hong Kong parent also owns businesses elsewhere in Asia or other jurisdictions, those affiliates may qualify as related parties. Depending on the ownership structure, transactions between the U.S. company and those entities can potentially trigger additional reporting.

This becomes particularly important for Hong Kong-headquartered groups with multiple subsidiaries, holding companies, or family-owned entities.

A separate Form 5472 is generally required for each reportable related party with which the reporting corporation had reportable transactions. As a result, identifying the complete related-party network is a fundamental part of the compliance process.

Who Can Be a Related Party?

One category involves a person or entity that directly or indirectly owns at least 25% of the U.S. company’s stock by vote or value. The analysis considers the relevant ownership interests rather than simply looking at the name appearing on a shareholder register.

Another category covers relationships defined under various provisions of U.S. tax law. Depending on the circumstances, these rules can capture relationships involving:

  • Family members
  • Corporations and their controlling shareholders
  • Companies belonging to the same controlled group
  • Partnerships under common ownership
  • Trusts, beneficiaries, grantors, and other trust relationships
  • Estates and their beneficiaries
  • Other entities connected through specified ownership relationships

For Hong Kong family-owned businesses, these rules can be especially important because business interests may be spread among family members, holding companies, trusts, and affiliated entities.

The analysis therefore needs to look beyond the U.S. company itself and consider its relationship with its 25% foreign shareholder and the broader ownership structure.

Why Sister Companies Can Create Reporting Issues

One of the easier relationships to overlook involves sister companies. Suppose a Hong Kong parent company owns a U.S. subsidiary as well as operating companies in Hong Kong, Mainland China, Singapore, or other markets.

Those Asian companies may have no direct ownership interest in the U.S. subsidiary. The U.S. company may not own them either.

Nevertheless, the companies may still be related for U.S. tax purposes because they are connected through their common parent.

This matters when transactions occur between the U.S. business and its overseas affiliates.

For example, the U.S. company might pay a Hong Kong affiliate for management services, purchase products from another group company, receive financing from its parent, or reimburse expenses incurred by an overseas affiliate.

Transactions of this nature should be reviewed as part of the Form 5472 analysis.

For a Hong Kong business group with several overseas entities, what initially appears to be a filing involving one foreign shareholder can therefore become a broader reporting exercise.

Formal Ownership Is Not Always the End of the Analysis

Another potential mistake is assuming that related-party status depends entirely on formal share ownership.

U.S. tax rules can look beyond legal form when determining whether common control exists. Depending on the applicable rule and circumstances, direct and indirect control, the economic relationship between businesses, and the way parties act in practice can become relevant.

This means a Hong Kong-owned U.S. business should not necessarily conclude that no related-party relationship exists simply because an overseas company does not appear on its ownership chart.

The substance of the relationship may need to be considered alongside the formal corporate structure.

Constructive Ownership Can Change the Result

Constructive ownership, sometimes called attribution, adds another layer to the analysis.

Under applicable U.S. tax rules, a person can sometimes be treated as owning shares that are legally held by certain family members or related entities.

As a result, someone who appears to own less than 25% of a U.S. company based solely on direct ownership could potentially meet the relevant threshold after the attribution rules are applied.

This issue deserves particular attention in family-owned Hong Kong businesses. For example, shares in a family enterprise may be divided among siblings or held through several family-controlled companies. Looking at each person’s direct percentage separately may not provide the complete answer under U.S. constructive ownership rules.

Ownership should therefore be analyzed under the applicable U.S. attribution provisions before concluding that a shareholder falls below the Form 5472 threshold.

Transactions Between the U.S. Company and Hong Kong Affiliates

Identifying the related parties is only part of the process. The business must also determine whether it had reportable transactions with those parties during the relevant tax year.

For a Hong Kong-owned U.S. company, transactions requiring review may include payments or transfers involving:

  • Sales and purchases of inventory or other property
  • Management or administrative services
  • Consulting and professional services
  • Royalties and licensing arrangements
  • Interest and financing
  • Loans or advances
  • Rent and leasing arrangements
  • Capital contributions
  • Distributions
  • Expense reimbursements
  • Other monetary and nonmonetary transactions

Intercompany activity that may seem routine from an operational perspective can still have U.S. reporting implications.

This is one reason Form 5472 compliance should be coordinated with the group’s accounting and transfer-pricing processes rather than addressed only when the U.S. tax return is being prepared.

Why Accurate Reporting Matters

Form 5472 carries significant penalties for noncompliance. A failure to file a required Form 5472, filing a substantially incomplete form, or failing to maintain required records can result in a substantial monetary penalty. Additional penalties may apply when a failure continues after notification by the IRS.

Where several related parties should have been reported, the exposure can increase because reporting requirements are evaluated separately.

For Hong Kong groups with numerous affiliates, this makes it particularly important to identify all potentially relevant entities before preparing the U.S. company’s annual filing.

Common Form 5472 Mistakes for Hong Kong-Owned Businesses

Several practical steps can reduce the risk of incomplete reporting:

  1. Look beyond the Hong Kong parent. Map the wider corporate group, including sister companies and other entities under common ownership or control.Review family ownership. For privately held and family-owned Hong Kong businesses, determine whether attribution rules alter the apparent ownership percentages.
  2. Consider existing trusts and holding companies. If shares are held through trusts, investment vehicles, or intermediate holding companies, the ownership analysis may require additional steps.
  3. Review intercompany transactions throughout the year. Payments between the U.S. entity and Hong Kong or other overseas affiliates should be identified and categorized rather than reconstructed at the last minute.
  4. Do not rely solely on the organization chart. Formal legal ownership is important, but it may not resolve every question concerning related-party status or control.
  5. Coordinate U.S. and Hong Kong finance teams. The information needed for Form 5472 may sit with accountants or finance personnel in Hong Kong rather than with the U.S. subsidiary.

A Practical Example

Consider a Hong Kong family that owns HK Holdings Ltd., which in turn owns a U.S. operating company.

HK Holdings also controls businesses in Hong Kong and Mainland China. During the year, the U.S. company purchases products from the Hong Kong affiliate, pays management fees to its parent, and receives an intercompany loan from another group entity.

It would be a mistake to review only the direct ownership of the U.S. company.

The broader group structure and each intercompany transaction need to be considered to determine which entities qualify as related parties and which transactions are reportable on Form 5472.

For larger Hong Kong groups, this exercise may need to extend across multiple levels of ownership and several jurisdictions.

Form 5472 FAQs for Hong Kong Businesses

1. Does a Hong Kong company with a U.S. subsidiary need to file Form 5472?

Potentially. Form 5472 generally applies to a 25% foreign-owned U.S. corporation that has reportable transactions with a foreign related party during the tax year. Special reporting rules can also apply to certain foreign-owned U.S. disregarded entities. The specific facts and entity classification should be reviewed.

2. Do transactions between a U.S. subsidiary and its Hong Kong parent need to be reported?

They may. Transactions between a U.S. reporting corporation and its foreign parent can fall within Form 5472’s reporting requirements. The nature and amount of the transactions should be reviewed under the applicable rules.

3. Can other companies owned by the Hong Kong parent be related parties?

Yes. Sister companies and other businesses within the same controlled group may qualify as related parties even when they do not directly own shares in the U.S. company.

4. Can family ownership affect Form 5472?

Yes. U.S. constructive ownership rules can attribute certain ownership interests between family members and through entities. This can affect whether a person is treated as meeting the relevant ownership threshold.

5. Does each foreign related party require a separate Form 5472?

Generally, a reporting corporation files a separate Form 5472 for each related party with which it had reportable transactions during the tax year. This makes identifying the complete related-party network particularly important for businesses belonging to larger international groups.

6. What are the penalites for not filing Form 5472?

Standard penalties are $25,000 per year, per form.

Review the Structure Before Filing

For Hong Kong businesses operating in the United States, Form 5472 compliance should not begin and end with the direct shareholder.

If you have questions about Form 5472 reporting for a Hong Kong-owned U.S. business, OLN’s US Tax Advisory Services team can help assess your ownership structure, related-party relationships, and U.S. reporting obligations. Contact us for guidance.

Disclaimer: This article is for reference only. Nothing herein shall be construed as Hong Kong legal advice or any legal advice for that matter to any person. Oldham, Li & Nie shall not be held liable for any loss and/or damage incurred by any person acting as a result of the materials contained in this article.

Filed Under: US Tax Advisory Services, 税務 Tagged With: Cross Border, Investment

Investing in the U.S.: What Hong Kong Families Should Know

2026年10月6日 by serena

For Hong Kong families, investing in the United States can provide access to attractive markets, diversification opportunities, and long-term wealth-building potential. But before capital is committed, it is important to consider how the investment will be owned and managed. The legal and tax structure chosen at the outset can significantly affect U.S. taxation, reporting obligations, liability, succession planning, and future flexibility.

For families and investors based in Hong Kong, a U.S. investment is rarely just a question of identifying the right asset. Whether the opportunity involves real estate, an operating business, private equity, or an investment portfolio, the way the investment is structured can be just as important as the investment itself.

This is particularly relevant for families whose assets, businesses, and family members may span Hong Kong, the United States, Mainland China, and other jurisdictions.

Decisions made before a transaction closes can have consequences for years – or even generations. A structure that appears straightforward today could create unexpected tax exposure, administrative requirements, or succession challenges later.

Start With the Ownership Strategy

There is no single structure that works for every investor entering the U.S. market. The appropriate approach depends on the investor’s circumstances, objectives, existing holdings, and connections to different jurisdictions.

Before selecting an entity or ownership arrangement, families should generally consider factors such as:

  • Hong Kong and other relevant tax residency considerations
  • The type and purpose of the U.S. investment
  • Long-term family and succession objectives
  • Potential exposure to U.S. estate tax
  • Existing trusts, companies, or family holding structures
  • Financing arrangements
  • The location and residency of family members and beneficiaries
  • Plans to sell, transfer, or pass the investment to future generations

These considerations are interconnected. A structure that is efficient for one family may be unnecessarily complicated – or potentially disadvantageous – for another.

Common Ways to Structure U.S. Investments

1. Limited Liability Companies (LLCs)

LLCs are frequently considered when international investors acquire U.S. assets or establish business operations. Depending on the circumstances, they can provide liability protection, management flexibility, and relatively straightforward ownership arrangements.

However, Hong Kong investors should not consider the U.S. treatment of an LLC in isolation. The way an entity is characterized and treated in other relevant jurisdictions may differ from its treatment under U.S. law.

This becomes particularly important for internationally mobile families or those with assets and family members in several countries. The analysis should therefore consider the broader cross-border implications before an LLC is established.

2. Corporations

A corporation may be appropriate for certain U.S. business investments, particularly where a company expects to grow, bring in additional investors, or establish substantial operations.

Corporate structures can offer practical advantages from an operational and governance perspective, but they may also introduce additional tax and compliance considerations.

Hong Kong investors should therefore evaluate the benefits of a corporate structure in the context of both the U.S. investment and their wider international arrangements.

3. Trusts

Trusts can play an important role for Hong Kong families concerned with preserving and transferring wealth across generations.

Depending on the family’s circumstances and applicable laws, trusts may support succession planning, asset protection, family governance, and estate planning objectives.

For Hong Kong families with beneficiaries, trustees, settlors, or assets located in different jurisdictions, however, trust planning can become particularly complex. U.S. rules governing trusts may interact with the family’s existing structures and the laws of other jurisdictions in ways that are not immediately apparent. This may be true even if the U.S. involvement is by beneficiaries that do not yet have transactions with the trust.

4. Partnerships and Joint Ventures

Partnership and joint venture arrangements can be useful when several family members, investors, or business partners want to participate in the same U.S. opportunity.

This may be particularly relevant to Hong Kong investors pursuing U.S. real estate, private business, or other investment opportunities alongside family members or investment partners.

These structures can offer considerable flexibility, but issues such as management authority, allocation of profits and losses, reporting responsibilities, transfer rights, and exit provisions should generally be addressed from the outset.

Don’t Underestimate U.S. Compliance Requirements

Completing the investment is only the beginning. Once an investor owns assets or conducts business in the United States, a range of U.S. reporting and compliance obligations may apply.

Depending on the structure and circumstances, these can include:

  • U.S. federal income tax returns
  • State-level tax filings
  • Information reporting requirements
  • Applicable ownership or disclosure requirements
  • Trust-related reporting
  • Entity filings and maintenance
  • Other cross-border reporting obligations

Missing an applicable filing can result in penalties, additional professional costs, and unnecessary administrative difficulties.

A common challenge for international families is that their advisors may be located in different jurisdictions. A Hong Kong accountant, U.S. attorney, wealth advisor, trustee, and other professionals may each be providing advice from a different perspective.

Each recommendation may make sense independently while creating unintended consequences when combined with the family’s wider international structure.

Coordinating Hong Kong and U.S. Planning

For Hong Kong families investing in the United States, coordination between advisors can be particularly important.

A typical transaction may involve U.S. attorneys and accountants alongside Hong Kong legal, tax, trust, banking, or wealth management professionals. Families with connections to additional jurisdictions may require an even broader advisory team.

For example, an ownership structure selected for a U.S. real estate investment could affect the family’s estate planning. Financing arrangements could influence how an investment is held or eventually transferred. An existing family trust or holding company could create considerations that would not arise for an individual investor.

When these issues are identified before a transaction is completed, families generally have more options for addressing them. Discovering them after closing can make restructuring considerably more difficult and expensive.

Why Planning Before the Investment Matters

Ideally, cross-border planning should begin before purchase agreements are finalized, entities are established, or investment funds are transferred from Hong Kong or elsewhere.

Early planning gives families an opportunity to consider the investment from several perspectives at once. It can help them:

  • Choose an appropriate ownership structure
  • Identify potential U.S. and cross-border tax consequences
  • Coordinate personal, family, and business objectives
  • Prepare for ongoing U.S. reporting and compliance
  • Understand relevant options considering the U.S. and Hong Kong do not have a Tax Treaty
  • Integrate the investment with existing family structures
  • Reduce unnecessary administrative complexity
  • Preserve flexibility for a future sale, transfer, or succession

The objective is not simply to complete a U.S. transaction efficiently. It is to establish a framework that continues to make sense as the investment -and the family’s circumstances – evolve.

Think Beyond the Initial U.S. Investment

For many Hong Kong families, an investment in the United States forms part of a much broader international wealth strategy.

A U.S. property acquisition may eventually become part of a family’s long-term investment portfolio. An initial business investment could lead to additional U.S. operations or acquisitions. A trust or holding structure established today may influence how wealth is managed and transferred to the next generation.

International mobility also matters. Children may study or live in the United States, family members may relocate, and business interests may expand into new jurisdictions. Changes of this kind can affect planning assumptions that were appropriate when an investment was first made.

Effective cross-border planning therefore looks beyond the immediate transaction.

Families should consider how a prospective U.S. investment fits with their existing assets, business interests, family arrangements, succession objectives, and overall global footprint.

Frequently Asked Questions for Hong Kong Investors

1. What is the best structure for a Hong Kong investor buying assets in the U.S.?

There is no universally preferable structure. The appropriate choice depends on factors including the nature of the investment, the investor’s tax residence, existing companies or trusts, financing requirements, succession objectives, and the jurisdictions with which the family has connections, and keeping in mind there is no Tax Treaty between the U.S. and Hong Kong.

2. Should a Hong Kong family use an LLC or a trust for a U.S. investment?

The two structures serve different purposes. An LLC may be useful for liability protection, management, and ownership flexibility, while a trust may have a greater role in succession, wealth preservation, and estate planning. Depending on the circumstances, more than one entity or structure may form part of the overall arrangement.

3. Do Hong Kong investors have U.S. tax and reporting obligations?

Potentially, yes. The requirements depend on the type of investment, ownership structure, activities conducted in the United States, and other circumstances. Obligations can include federal and state tax filings, information returns, trust reporting, entity filings, and other applicable disclosures. Additionally, without a proper structure, U.S. assets could be subject ot the estate tax.

4. Why should Hong Kong investors plan before transferring funds to the U.S.?

Decisions about ownership and structure can be considerably easier to implement before an investment is completed. Reviewing the U.S. tax, legal, succession, and compliance implications in advance can help avoid unnecessary restructuring and preserve greater flexibility later.

5. Why is cross-border coordination particularly important for Hong Kong families?

Hong Kong families may have assets, companies, trusts, beneficiaries, or family members across several jurisdictions. A decision that works well from a U.S. perspective may have different consequences elsewhere. Coordinating U.S. and Hong Kong advisors – and advisors in any other relevant jurisdictions – helps ensure that the investment is considered as part of the family’s overall wealth and succession strategy. OLN has a dedicated US Tax Advisory Services practice in Hong Kong. Contact us for guidance.

Disclaimer: This article is for reference only. Nothing herein shall be construed as Hong Kong legal advice or any legal advice for that matter to any person. Oldham, Li & Nie shall not be held liable for any loss and/or damage incurred by any person acting as a result of the materials contained in this article.

Filed Under: US Tax Advisory Services, 税務 Tagged With: Cross Border, Investment

The End of the “418 Rule”: What Employers in Hong Kong Need to Know About the New “417/468” Continuous Contract Requirement

2026年9月11日 by OLN Marketing

Introduction

For decades, whether an employee was regarded as employed under a “continuous contract” under the Employment Ordinance (Cap. 57) (“EO”) depended on the “418 rule”: the employee had to be employed continuously by the same employer for four weeks or more and work at least 18 hours in each week. Continuous contract status matters because it is the gateway to important statutory protections and benefits, including paid annual leave, statutory holiday pay, sickness allowance, maternity and paternity leave, severance payment and long service payment.

With effect from 18 January 2026, the “418 rule” has been replaced by a more flexible “417/468” framework. Under the new requirement, an employee will be regarded as employed under a “continuous contract” if they have been employed continuously by the same employer for four weeks or more and either: (i) worked at least 17 hours in each week; or (ii) where they worked less than 17 hours in any week, worked 68 hours or more in the four-week period comprising that week and the three weeks immediately preceding it. This article explains the new threshold, why the rolling four-week calculation matters, and which industries and working arrangements are likely to be most affected.

“Continuous Contract”

The practical concept and threshold of a “continuous contract” is fundamental to Hong Kong employment law. By virtue of satisfying this threshold, employees access a broad array of statutory protections and entitlements, subject in each case to the employee satisfying the applicable eligibility conditions for that particular benefit, including:-

  • Annual leave and statutory holidays;
  • Sickness allowance and maternity/paternity leave;
  • Severance payment and long service payment; and
  • Protection against unreasonable dismissal.

The New “Continuous Contract” Threshold: From “418” to “417/468”

A comparison of the old and new requirements is as follows:-

Definition of “continuous contract” under “418 rule”
(effective before 18 January 2026)
Definition of “continuous contract” under new “417/468 rule”
(effective on or after 18 January 2026)
Employee works 18 or more hours per week for four consecutive weeks.Employee works at least 17 hours in each week for four or more consecutive weeks; OR 
Where the employee works less than 17 hours in any week, the employee works 68 hours or more in the four-week period comprising that week and the three weeks immediately preceding that week. The 468 limb does not apply during the first three weeks of a new employment.

In particular, under “468 rule”, rather than measuring hours on a week-by-week basis, it looks at an employee’s aggregate working hours across a rolling four-week window. This makes it far harder for employers to sidestep the threshold by varying rosters from week to week. For illustration, an employee whose hours fluctuate between 10 and 22 hours per week may well qualify, even if they never consistently exceed 17 hours in any given week.

In particular, the “468 rule” is significant because it moves the analysis beyond a simple week-by-week threshold. Where an employee works less than 17 hours in a given week, employers must look at the employee’s aggregate working hours across that week and the three immediately preceding weeks. This makes fluctuating rosters more important: a shorter week will not necessarily prevent continuous contract status if the rolling four-week total reaches 68 hours, although the assessment remains fact-sensitive and the 468 limb will not assist during the first three weeks of a new employment.

Crucially, under section 3(2) of the EO, the burden of proving that an employment contract is not a continuous contract lies with the employer in the event of a dispute.

Impact on the Employment Landscape

The practical ramifications of this amendment are significant and broad-reaching.

Part-time, casual, seasonal and variable-hours workers are likely to be the primary beneficiaries. The sectors most directly affected are those with heavy reliance on shift-based or fluctuating staffing, including retail, catering, hospitality, food and beverage, entertainment, logistics, events and promotional work. Platform or gig-style arrangements may also require closer review where the underlying relationship is, in substance, employment rather than genuine self-employment.

Meanwhile, employers face a corresponding increase in compliance and administration obligations. Businesses that previously relied on the 18-hour weekly threshold, or rostered staff close to that threshold, should reassess their workforce structures, contracts, payroll rules and timekeeping systems. Key areas of review include:-

  • Employees newly qualifying as continuous contract employees may become entitled to statutory benefits, requiring payroll and benefits recalculation.
  • Employment contracts, staff handbooks and rostering policies that refer to the old “418 rule” or assume a fixed 18-hour weekly threshold should be reviewed and updated.
  • Given the combined “417/468” framework, employers should track both weekly hours and rolling four-week totals, and maintain robust timekeeping and payroll records to determine eligibility and support the employer’s position in any dispute.
  • Severance and long service exposure: As more workers qualify as continuous contract employees, employer exposure to severance payment and long service payment claims, as well as holiday, sickness and leave-related costs, may increase.

How can OLN help?

The replacement of the “418 rule” with the new “417/468” continuous contract requirement represents one of the most significant expansions of statutory employment protection in Hong Kong in recent years. For businesses with part-time, casual, seasonal, event-based or variable-hours staff, the implications are immediate and wide-ranging.

Our team at OLN can assist with workforce audits to identify employees who now qualify, or may soon qualify, as continuous contract employees; review and update employment contracts, staff handbooks and rostering practices to reflect the new threshold; and advise on statutory entitlements, payroll administration, record-keeping and dispute risk under the amended framework.

Should you have any questions, please feel free to contact us.

Disclaimer: This article is for reference only. Nothing herein shall be construed as Hong Kong legal advice or legal advice of any kind to any person. Oldham, Li & Nie shall not be held liable for any loss and/or damage incurred by any person acting as a result of the materials contained in this article.
Filed Under: カテゴリーなし, 人事労務・就労系ビザ関連法

The Rise of the Employer of Record in Hong Kong and How Businesses Can Leverage It

2026年9月11日 by OLN Marketing

Introduction

Hong Kong’s employment landscape is changing. The recent amendment to the Employment Ordinance (Cap. 57) (“EO”), which introduces a broader continuous contract threshold from 18 January 2026, is one of several developments that should prompt businesses to take a closer look at how they structure and manage their workforce. For many, that review may well lead them to an increasingly familiar solution: the Employer of Record.

The Employer of Record (“EOR”) model is not new, but its profile in Hong Kong has grown considerably in recent years. Fuelled by the rise of cross-border hiring, more flexible workforce models, and a steady expansion of statutory employment obligations, more businesses are turning to EOR arrangements to simplify the way they engage workers. The appeal is understandable. There are, however, risks that businesses should plan against.

The EOR Model

An EOR is a third-party entity that formally acts as the employer on record of workers on behalf of a client company. In a typical EOR arrangement, the EOR signs the employment contract and handles payroll, MPF enrolment and contributions, employer tax reporting and other employment administration, while the client company retains day-to-day operational control over the workers’ activities.

The tripartite EOR structure is, in essence, as follows:

  • The EOR employs the workers on paper and manages agreed compliance obligations;
  • The client company directs the workers’ daily tasks and business activities; and
  • The employees are formally contracted to the EOR but functionally serve the client.

The EOR model has found particular appeal among businesses seeking to expand into new markets without the delay and cost of establishing a local entity, as well as multinationals looking to centralise employment administration across jurisdictions.

The Benefits of EOR

In light of the new continuous contract framework, EOR arrangements offer a number of practical attractions for Hong Kong businesses.

  1. The EOR can take responsibility for monitoring evolving statutory requirements and managing outsourced compliance processes so that employment contracts, payroll systems and benefits structures reflect the applicable law.
  2. Businesses can engage talent quickly, without setting up a local entity and without having to build the full local employment administration infrastructure themselves. This can reduce costs and increase efficiency.
  3. The administrative burden on internal HR departments is also reduced. Payroll calculations, MPF enrolment and contributions, employer reporting to the Inland Revenue Department (“IRD”) under the salaries tax regime, and statutory leave tracking can all handled by the EOR.
  4. Companies considering a Hong Kong presence can hire locally on a trial basis through an EOR before committing to a formal corporate structure, allowing them to conduct market testing before committing capital and labour for the long term.

Key EOR Risks to Consider

Despite its commercial appeal, the EOR model carries meaningful legal and operational risks that businesses should evaluate carefully before proceeding.

1. Risk of Being Deemed the True Employer

Under Hong Kong law, the question of who is the “employer” for the purposes of the EO may turn on the substance of the relationship, not merely the label assigned to it. The courts and tribunals may examine the reality of the arrangement. If the client company:

  • exercises substantial control over the worker’s day-to-day activities;
  • provides the worker’s equipment, workspace, and tools;
  • integrates the worker into its own organisational structure; or
  • fails to maintain a meaningful distinction between its own staff and the EOR-engaged worker,

there is a risk that the client company may be found to be the worker’s true employer, depending on the facts, notwithstanding the contractual position with the EOR. This could expose the client to EO-related liabilities, including obligations relating to severance payment, statutory holiday pay, annual leave, sickness allowance and claims for unreasonable dismissal.

2. Employment Agency Regulations

The EOR model, if not properly structured, may also raise employment agency licensing issues. Employment agencies are regulated under the  EO and the Employment Agency Regulations (Cap. 57A), and employment agencies must generally be licensed by the Labour Department. An EOR that functions essentially as a broker, by introducing or placing workers with client companies without genuinely acting as the substantive employer, may risk being treated as an unlicensed employment agency, with attendant regulatory and criminal exposure.

3. MPF and Salaries Tax Obligations

Even where an EOR arrangement is properly structured, client companies should satisfy themselves that the EOR is enrolling eligible employees in an MPF scheme within the statutory framework, making timely and correct MPF contributions, and filing accurate employer returns and related IR56 forms with the IRD. The statutory obligation to make MPF contributions sits with the employer of record, but reputational and operational risks can flow back to the client if an EOR defaults on these obligations.

4. Permanent Establishment Risk

For overseas companies engaging workers in Hong Kong through an EOR, there may also be Hong Kong profits tax risk if the worker’s activities constitute a permanent establishment in Hong Kong or otherwise result in Hong Kong sourced profit for Profits Tax purposes, particularly if they involve entering into contracts on the company’s behalf. Businesses should take advice on this risk before deploying an EOR arrangement, particularly where the engaged workers exercise significant commercial discretion.

5. Continuity of Employment and the “417/468 Rule”

Under the new framework, businesses that rotate EOR-engaged workers through consecutive contracts must be vigilant. From 18 January 2026, an employee is regarded as employed under a continuous contract if the employee has been continuously employed by the same employer for four weeks or more and either works at least 17 hours in each week or, where the employee works less than 17 hours in a week, has worked 68 hours or more in the four-week period comprising that week and the preceding three weeks. The “468 Rule” does not apply to the first three weeks of a new employment, and attempts to structure arrangements to avoid statutory entitlements may create additional legal and reputational risk.

How can OLN help?

OLN has extensive experience advising businesses, from market entrants to established multinationals, on the full spectrum of employment issues in Hong Kong. Whether you are considering an EOR arrangement for the first time, reviewing an existing structure for compliance risk, or navigating the implications of the new continuous contract framework, our team can help you assess your exposure and structure your workforce arrangements on a sound legal footing.

Should you have any questions, please feel free to contact us.

Disclaimer: This article is for reference only. Nothing herein shall be construed as Hong Kong legal advice or legal advice of any kind to any person. Oldham, Li & Nie shall not be held liable for any loss and/or damage incurred by any person acting as a result of the materials contained in this article.

Filed Under: カテゴリーなし, 人事労務・就労系ビザ関連法

Hong Kong Succession Guide – What Happens to Hong Kong Assets When a Mainland Entrepreneur Passes Away

2026年9月3日 by OLN Marketing

When a mainland Chinese entrepreneur dies, leaving assets in the Hong Kong SAR, the assets do not automatically transfer to family members. The Hong Kong SAR has its own legal system and probate process, which must be followed before assets can be accessed or distributed to the deceased’s heirs. This article briefly explains the Hong Kong SAR legal process to distribute a deceased’s assets.

First step: Are there assets in Hong Kong?

The first step would be to determine which assets fall within the legal jurisdiction of the Hong Kong SAR. These assets may include bank accounts held with Hong Kong banking institutions, shares held in Hong Kong companies, real property (real estate) held in Hong Kong and/or securities traded on the Hong Kong Stock Exchange. The administration of the above types of assets would be dealt with through the Hong Kong court process and Hong Kong law will generally govern Hong Kong real estate, regardless of the deceased’s nationality or place of residence.

The legal authority to deal with the deceased’s Hong Kong assets is granted by the High Court of Hong Kong either in the form of a grant of probate (if the deceased left a valid will naming an executor who is willing to act) or a type of letters of administration, if the deceased left no will, the will is invalid or no executor is able to act.

Did the deceased leave a Will?

If the deceased left a Will, the Hong Kong court will need to decide whether the Will is valid under Hong Kong law and whether it covers Hong Kong assets. Hong Kong recognises Wills executed in accordance with the law of the place of execution or the deceased’s domicile. If the Will was executed in the People’s Republic of China (“PRC”), issues that sometimes arise include the differences in formal requirements between the two jurisdictions, lack of clarity over asset coverage and the absence of an appointed executor. If an executor is named in the Will, the executor (usually with the help of his/her Hong Kong solicitor) applies for probate in Hong Kong.

What if the deceased left no Will or an invalid Will?

If the deceased left no Will or an invalid Will, this is deemed an intestacy and the deceased’s estate will be distributed in accordance with Hong Kong’s intestacy rules pursuant to the Intestates’ Estates Ordinance Cap 73.

Who are the heirs in an intestacy?

Very broadly speaking, the surviving spouse (with a fixed statutory legacy in specific situations) and children take priority and extended family members such as parents and siblings inherit only if closer relatives do not exist.  A suitable family member (often the surviving spouse or an adult child) applies for Letters of Administration in order to administer the estate.

What are the documents generally required of PRC heirs?

PRC heirs are typically required to present the following documentation – death certificate issued by mainland Chinese authorities, resident identity cards of the deceased and heirs, hukou registration records to prove family relationships, marriage or divorce documents if applicable and notarial certificates confirming identity and kinship. In practice, Hong Kong courts usually require these documents to be notarised by a notary public in the PRC and properly authenticated (for example, via current apostille/legalisation arrangements).

What if probate proceedings have already been completed in the PRC?

Even if probate proceedings have already been completed in the PRC, it is not possible to apply for recognition of these probate documents in Hong Kong. Unfortunately the PRC is not listed as a country under Hong Kong’s statutory resealing regime as the listed countries are all common law regimes. A fresh application in Hong Kong is required.

Are there estate duties and estate taxes in Hong Kong?

Estate duties have been abolished in Hong Kong for deaths occurring after 11 February 2006 and there have never been estate or inheritance taxes. However, tax issues may arise in the PRC and other applicable jurisdictions.

What are some practical challenges faced by PRC heirs?

As a result of the numerous complications mentioned above, some common challenges faced by PRC heirs include delays due to incomplete documentation, difficulty proving family relationships where hukou registration records differ from actual family relationships, translation (from Chinese to English) as well as notarisation requirements and disputes over the validity or interpretation of Wills (the latter complication is not unique to PRC heirs but occurs across all jurisdictions).

It is important to note that if the deceased was domiciled in the PRC, PRC succession law may be relevant in deciding who inherits movable assets in Hong Kong, although the Hong Kong court issues the grant and supervises the administration.

What is the expected timeline?

A straightforward probate application in Hong Kong takes a few months to complete. Complex cross-border estates take longer, particularly where there is no will, documents must be obtained from mainland authorities and/or heirs are in dispute about their entitlements.

Does planning ahead help?

For PRC citizens with assets in Hong Kong, advance planning can significantly reduce complications in the probate process. Many have opted to execute separate Hong Kong wills to cover their Hong Kong assets to streamline the legal process in Hong Kong, appointed executors familiar with Hong Kong laws and maintained clear records of bank accounts, shareholdings, property and other assets.

Conclusion

The passing of a loved one is one of the most difficult times in a person’s life. With the benefit of advance legal planning, heirs will be able to navigate the complicated process of probate more smoothly and avoid unnecessary stress during a time of immense grief. And with a properly drafted will, one can generally choose who should inherit one’s assets, without regard to fixed intestacy rules in Hong Kong.

In conclusion, it is advisable to seek professional legal advice if one’s estate involves Hong Kong assets.

Disclaimer: This article is for reference only. Nothing herein shall be construed as Hong Kong legal advice or any legal advice for that matter to any person. Oldham, Li & Nie shall not be held liable for any loss and/or damage incurred by any person acting as a result of the materials contained in this article.

Filed Under: カテゴリーなし, Elder Law Practice Group, プライベートクライアント Tagged With: Estate planning

  • Page 1
  • Page 2
  • Page 3
  • Interim pages omitted …
  • Page 56
  • Go to Next Page »

Primary Sidebar

This website uses cookies to optimise your experience and to collect information to customise content. By closing this banner, clicking a link or continuing to browse otherwise, you agree to the use of cookies. Please read the cookies section of our Privacy Policy to learn more. Learn more

Footer

OLN logo

Suite 503, 5/F, St George's Building
2 Ice House Street, Central
Hong Kong

Tel. +852 2868 0696 | Email us
について 弁護士紹介 事業拠点 OLN IP Services プライバシーポリシー
業務内容 インサイト 採用情報 OLN Online
について 業務内容 弁護士紹介 インサイト 事業拠点
採用情報 OLN IP Services OLN Online プライバシーポリシー
linkedin twitter facebook
OLN logo

© 2026 Oldham, Li & Nie. All Rights Reserved.

Manage Consent
To provide the best experiences, we use technologies like cookies to store and/or access device information. Consenting to these technologies will allow us to process data such as browsing behavior or unique IDs on this site. Not consenting or withdrawing consent, may adversely affect certain features and functions.
Functional Always active
The technical storage or access is strictly necessary for the legitimate purpose of enabling the use of a specific service explicitly requested by the subscriber or user, or for the sole purpose of carrying out the transmission of a communication over an electronic communications network.
Preferences
The technical storage or access is necessary for the legitimate purpose of storing preferences that are not requested by the subscriber or user.
Statistics
The technical storage or access that is used exclusively for statistical purposes. The technical storage or access that is used exclusively for anonymous statistical purposes. Without a subpoena, voluntary compliance on the part of your Internet Service Provider, or additional records from a third party, information stored or retrieved for this purpose alone cannot usually be used to identify you.
Marketing
The technical storage or access is required to create user profiles to send advertising, or to track the user on a website or across several websites for similar marketing purposes.
  • Manage options
  • Manage services
  • Manage {vendor_count} vendors
  • Read more about these purposes
View preferences
  • {title}
  • {title}
  • {title}
お問い合わせ

メッセージの詳細をここで共有してください。すぐにご連絡させていただきます。

    x