• Skip to primary navigation
  • Skip to main content
  • Skip to primary sidebar
  • Skip to footer
location iconSuite 503, 5/F, St. George's Building, 2 Ice House Street, Central, Hong Kongphone-icon +852 2868 0696 linkedintwitterfacebook
OLN IP Services
close-btn
OLN IP Services
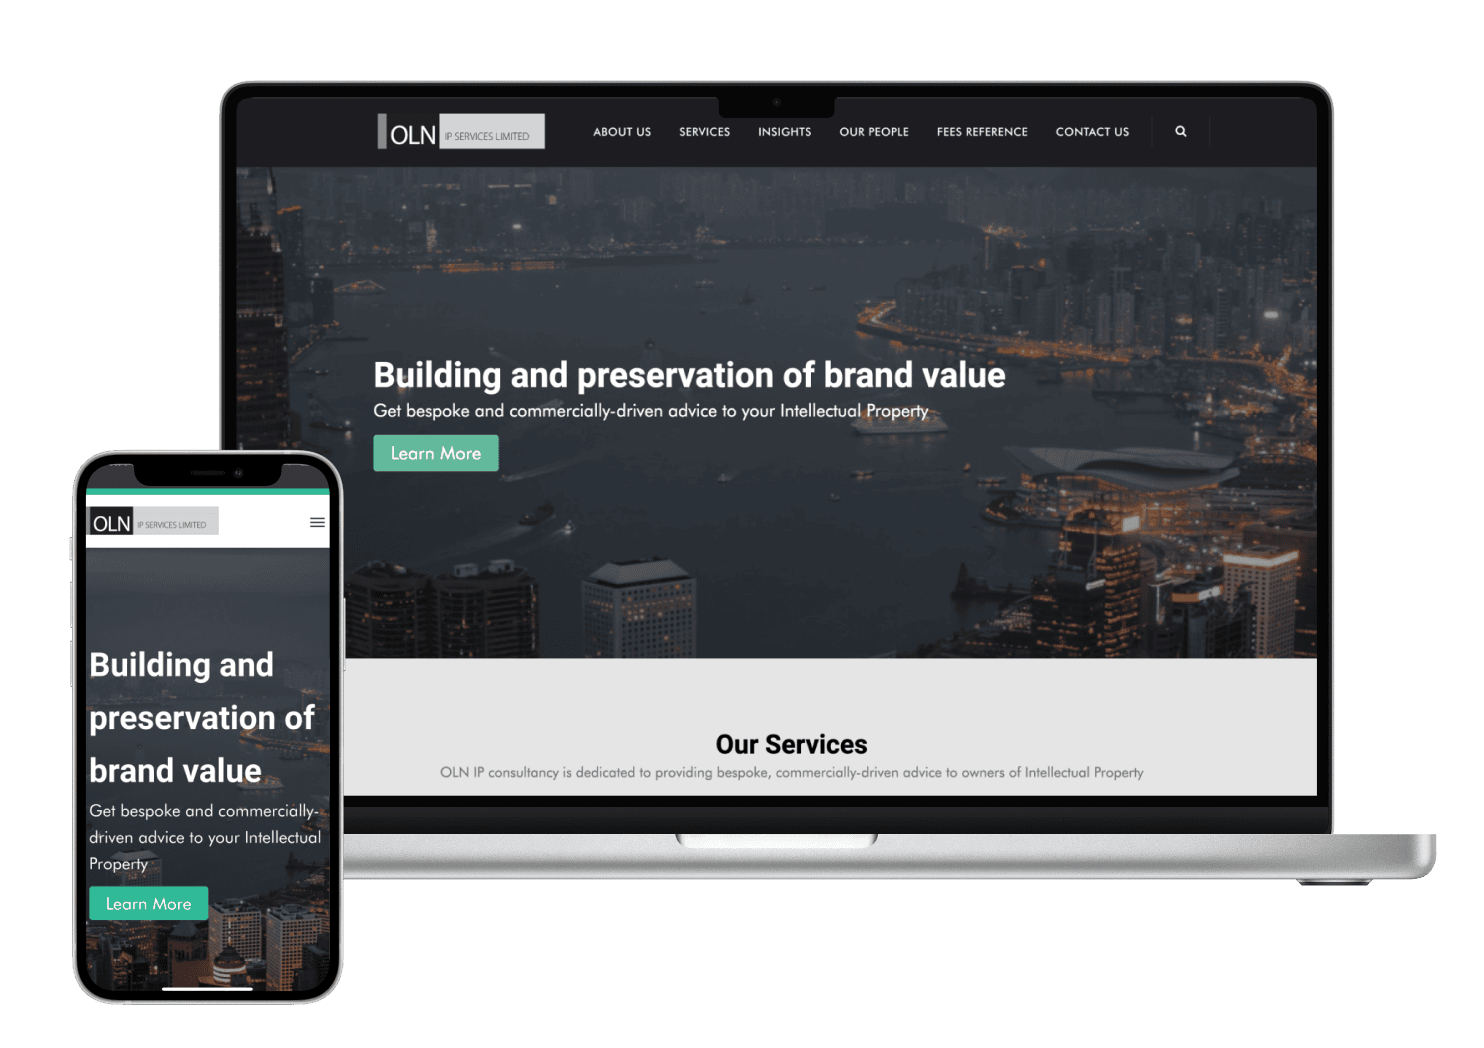
Get bespoke and commercially-driven advice to your Intellectual Property
Learn More
OLN IP Services
OLN Online
close-btn
OLN Online
Powered by Oldham, Li & Nie, the law firm of choice for Hong Kong’s vibrant startup and SME community, OLN Online is a forward-looking and seamless addition to traditional legal services – a true disruptor.
Learn More
OLN IP Services
OLN CS
close-btn
OLN CS
OLN was established in 1987 by Gordon Oldham with the goal of providing both quality legal advice and practical legal solutions to the business community.
Learn More
OLN CS Services
  • ENG
    • 简
    • 繁
    • FR
    • 日本語
    • IT
Oldham, Li & Nie
OLN IP Services
close-btn
OLN IP Services
Get bespoke and commercially-driven advice to your Intellectual Property
Learn More
OLN IP Services
OLN Online
OLN CS
close-btn
OLN Online
Powered by Oldham, Li & Nie, the law firm of choice for Hong Kong’s vibrant startup and SME community, OLN Online is a forward-looking and seamless addition to traditional legal services – a true disruptor.
Learn More
OLN IP Services
  • About
        • Awards & Rankings
        • Corporate Social Responsibility
  • Practice Areas
        • Canadian Notarization Services
        • Commercial Fraud & Asset Tracing
        • Elder Law Practice Group
        • Family Office Services
        • Fund Practice
        • Intellectual Property Law
        • Notarial Services
        • Regulatory Compliance, Investigations and Enforcement
        • China Practice
        • Corporate & Commercial Law
        • Employment & Business Immigration Law
        • Financial Service & Regulatory
        • Insolvency & Restructuring Law
        • Italian Practice
        • Personal Injury Law
        • Startups & Venture Capital
        • Chinese Notary Services (CAAO)
        • Dispute Resolution
        • Family Law
        • French Practice
        • Insurance Law
        • Japanese Practice
        • Private Client – Estate Planning & Probate
        • Tax Advisory
        • Canadian Notarization Services
        • China Practice
        • Chinese Notary Services (CAAO)
        • Commercial Fraud and Asset Tracing
        • Corporate and Commercial Law
        • Dispute Resolution
        • Elder Law Practice Group
        • Employment and Business Immigration Law
        • Family Law
        • Financial Service and Regulatory
        • French Practice
        • Fund Practice
        • Insolvency & Restructuring Law
        • Insurance Law
        • Intellectual Property Law
        • Italian Practice
        • Japanese Practice
        • Notarial Services
        • Personal Injury Law
        • Private Client – Estate Planning and Probate
        • Regulatory Compliance, Investigations and Enforcement
        • Startups & Venture Capital
        • Tax Advisory
        • U.S. Tax Advisory Services
  • People
  • Insights
  • Offices

Suite 503, St. George's Building,
2 Ice House Street, Central, Hong Kong

Tel. +852 2868 0696 | Send Email
linkedin twitter facebook
OLN Blue

OLN Law

  • About
    • Awards and Rankings
    • Corporate Social Responsibility
  • Awards and Rankings
  • Block Content Examples
  • Careers
  • Client Information & Registration
  • Contact Us
  • Cookie Policy (EU)
  • Globalaw
  • Offices
  • Oldham, Li & Nie
  • OLN Podcasts
  • People
  • Practice Areas
  • Privacy Policy
  • Review
  • Reviews
  • Standard Terms of Engagement
  • About
        • Awards & Rankings
        • Corporate Social Responsibility
  • Practice Areas
        • Canadian Notarization Services
        • Commercial Fraud & Asset Tracing
        • Elder Law Practice Group
        • Family Office Services
        • Fund Practice
        • Intellectual Property Law
        • Notarial Services
        • Regulatory Compliance, Investigations and Enforcement
        • China Practice
        • Corporate & Commercial Law
        • Employment & Business Immigration Law
        • Financial Service & Regulatory
        • Insolvency & Restructuring Law
        • Italian Practice
        • Personal Injury Law
        • Startups & Venture Capital
        • Chinese Notary Services (CAAO)
        • Dispute Resolution
        • Family Law
        • French Practice
        • Insurance Law
        • Japanese Practice
        • Private Client – Estate Planning & Probate
        • Tax Advisory
        • Canadian Notarization Services
        • China Practice
        • Chinese Notary Services (CAAO)
        • Commercial Fraud and Asset Tracing
        • Corporate and Commercial Law
        • Dispute Resolution
        • Elder Law Practice Group
        • Employment and Business Immigration Law
        • Family Law
        • Financial Service and Regulatory
        • French Practice
        • Fund Practice
        • Insolvency & Restructuring Law
        • Insurance Law
        • Intellectual Property Law
        • Italian Practice
        • Japanese Practice
        • Notarial Services
        • Personal Injury Law
        • Private Client – Estate Planning and Probate
        • Regulatory Compliance, Investigations and Enforcement
        • Startups & Venture Capital
        • Tax Advisory
        • U.S. Tax Advisory Services
  • People
  • Insights
  • Offices

Form 5472 Reporting: What Hong Kong-Owned U.S. Businesses Need to Know

Cross Border

Form 5472 Reporting: What Hong Kong-Owned U.S. Businesses Need to Know

October 6, 2026 by serena

For Hong Kong families, investing in the United States can provide access to attractive For Hong Kong businesses with U.S. subsidiaries or other U.S. entities, Form 5472 reporting may extend well beyond the company’s direct Hong Kong owner. Related companies, family members, affiliated entities, and businesses under common control can potentially come into the analysis. Understanding these relationships is an important part of meeting U.S. reporting obligations and avoiding substantial penalties.

Hong Kong companies expanding into the United States often focus first on operational matters – establishing a U.S. entity, opening bank accounts, hiring employees, entering contracts, or acquiring assets.

But establishing a U.S. presence can also create important federal tax reporting obligations.

One of these is IRS Form 5472, an information return that can apply when a U.S. corporation is at least 25% foreign owned and has reportable transactions with foreign related parties during the tax year. Certain foreign-owned U.S. disregarded entities are also subject to Form 5472 reporting under special rules. The penalties for not filing are severe. Even though the form is relatively short, the penalty is $25,000 per year, per form, for each non filing violation.

For a U.S. company owned by a Hong Kong business or individual, determining who must be reported is not always as simple as identifying the shareholder listed on the company’s records.

U.S. tax rules can extend the analysis to a much broader network of related individuals and businesses.

Form 5472 and Hong Kong Business Groups

At first glance, the ownership structure might appear straightforward: the Hong Kong parent owns the U.S. company, so the parent is the foreign owner relevant to the Form 5472 analysis.

But the reporting analysis may not end there.

If the Hong Kong parent also owns businesses elsewhere in Asia or other jurisdictions, those affiliates may qualify as related parties. Depending on the ownership structure, transactions between the U.S. company and those entities can potentially trigger additional reporting.

This becomes particularly important for Hong Kong-headquartered groups with multiple subsidiaries, holding companies, or family-owned entities.

A separate Form 5472 is generally required for each reportable related party with which the reporting corporation had reportable transactions. As a result, identifying the complete related-party network is a fundamental part of the compliance process.

Who Can Be a Related Party?

One category involves a person or entity that directly or indirectly owns at least 25% of the U.S. company’s stock by vote or value. The analysis considers the relevant ownership interests rather than simply looking at the name appearing on a shareholder register.

Another category covers relationships defined under various provisions of U.S. tax law. Depending on the circumstances, these rules can capture relationships involving:

  • Family members
  • Corporations and their controlling shareholders
  • Companies belonging to the same controlled group
  • Partnerships under common ownership
  • Trusts, beneficiaries, grantors, and other trust relationships
  • Estates and their beneficiaries
  • Other entities connected through specified ownership relationships

For Hong Kong family-owned businesses, these rules can be especially important because business interests may be spread among family members, holding companies, trusts, and affiliated entities.

The analysis therefore needs to look beyond the U.S. company itself and consider its relationship with its 25% foreign shareholder and the broader ownership structure.

Why Sister Companies Can Create Reporting Issues

One of the easier relationships to overlook involves sister companies. Suppose a Hong Kong parent company owns a U.S. subsidiary as well as operating companies in Hong Kong, Mainland China, Singapore, or other markets.

Those Asian companies may have no direct ownership interest in the U.S. subsidiary. The U.S. company may not own them either.

Nevertheless, the companies may still be related for U.S. tax purposes because they are connected through their common parent.

This matters when transactions occur between the U.S. business and its overseas affiliates.

For example, the U.S. company might pay a Hong Kong affiliate for management services, purchase products from another group company, receive financing from its parent, or reimburse expenses incurred by an overseas affiliate.

Transactions of this nature should be reviewed as part of the Form 5472 analysis.

For a Hong Kong business group with several overseas entities, what initially appears to be a filing involving one foreign shareholder can therefore become a broader reporting exercise.

Formal Ownership Is Not Always the End of the Analysis

Another potential mistake is assuming that related-party status depends entirely on formal share ownership.

U.S. tax rules can look beyond legal form when determining whether common control exists. Depending on the applicable rule and circumstances, direct and indirect control, the economic relationship between businesses, and the way parties act in practice can become relevant.

This means a Hong Kong-owned U.S. business should not necessarily conclude that no related-party relationship exists simply because an overseas company does not appear on its ownership chart.

The substance of the relationship may need to be considered alongside the formal corporate structure.

Constructive Ownership Can Change the Result

Constructive ownership, sometimes called attribution, adds another layer to the analysis.

Under applicable U.S. tax rules, a person can sometimes be treated as owning shares that are legally held by certain family members or related entities.

As a result, someone who appears to own less than 25% of a U.S. company based solely on direct ownership could potentially meet the relevant threshold after the attribution rules are applied.

This issue deserves particular attention in family-owned Hong Kong businesses. For example, shares in a family enterprise may be divided among siblings or held through several family-controlled companies. Looking at each person’s direct percentage separately may not provide the complete answer under U.S. constructive ownership rules.

Ownership should therefore be analyzed under the applicable U.S. attribution provisions before concluding that a shareholder falls below the Form 5472 threshold.

Transactions Between the U.S. Company and Hong Kong Affiliates

Identifying the related parties is only part of the process. The business must also determine whether it had reportable transactions with those parties during the relevant tax year.

For a Hong Kong-owned U.S. company, transactions requiring review may include payments or transfers involving:

  • Sales and purchases of inventory or other property
  • Management or administrative services
  • Consulting and professional services
  • Royalties and licensing arrangements
  • Interest and financing
  • Loans or advances
  • Rent and leasing arrangements
  • Capital contributions
  • Distributions
  • Expense reimbursements
  • Other monetary and nonmonetary transactions

Intercompany activity that may seem routine from an operational perspective can still have U.S. reporting implications.

This is one reason Form 5472 compliance should be coordinated with the group’s accounting and transfer-pricing processes rather than addressed only when the U.S. tax return is being prepared.

Why Accurate Reporting Matters

Form 5472 carries significant penalties for noncompliance. A failure to file a required Form 5472, filing a substantially incomplete form, or failing to maintain required records can result in a substantial monetary penalty. Additional penalties may apply when a failure continues after notification by the IRS.

Where several related parties should have been reported, the exposure can increase because reporting requirements are evaluated separately.

For Hong Kong groups with numerous affiliates, this makes it particularly important to identify all potentially relevant entities before preparing the U.S. company’s annual filing.

Common Form 5472 Mistakes for Hong Kong-Owned Businesses

Several practical steps can reduce the risk of incomplete reporting:

  1. Look beyond the Hong Kong parent. Map the wider corporate group, including sister companies and other entities under common ownership or control.Review family ownership. For privately held and family-owned Hong Kong businesses, determine whether attribution rules alter the apparent ownership percentages.
  2. Consider existing trusts and holding companies. If shares are held through trusts, investment vehicles, or intermediate holding companies, the ownership analysis may require additional steps.
  3. Review intercompany transactions throughout the year. Payments between the U.S. entity and Hong Kong or other overseas affiliates should be identified and categorized rather than reconstructed at the last minute.
  4. Do not rely solely on the organization chart. Formal legal ownership is important, but it may not resolve every question concerning related-party status or control.
  5. Coordinate U.S. and Hong Kong finance teams. The information needed for Form 5472 may sit with accountants or finance personnel in Hong Kong rather than with the U.S. subsidiary.

A Practical Example

Consider a Hong Kong family that owns HK Holdings Ltd., which in turn owns a U.S. operating company.

HK Holdings also controls businesses in Hong Kong and Mainland China. During the year, the U.S. company purchases products from the Hong Kong affiliate, pays management fees to its parent, and receives an intercompany loan from another group entity.

It would be a mistake to review only the direct ownership of the U.S. company.

The broader group structure and each intercompany transaction need to be considered to determine which entities qualify as related parties and which transactions are reportable on Form 5472.

For larger Hong Kong groups, this exercise may need to extend across multiple levels of ownership and several jurisdictions.

Form 5472 FAQs for Hong Kong Businesses

1. Does a Hong Kong company with a U.S. subsidiary need to file Form 5472?

Potentially. Form 5472 generally applies to a 25% foreign-owned U.S. corporation that has reportable transactions with a foreign related party during the tax year. Special reporting rules can also apply to certain foreign-owned U.S. disregarded entities. The specific facts and entity classification should be reviewed.

2. Do transactions between a U.S. subsidiary and its Hong Kong parent need to be reported?

They may. Transactions between a U.S. reporting corporation and its foreign parent can fall within Form 5472’s reporting requirements. The nature and amount of the transactions should be reviewed under the applicable rules.

3. Can other companies owned by the Hong Kong parent be related parties?

Yes. Sister companies and other businesses within the same controlled group may qualify as related parties even when they do not directly own shares in the U.S. company.

4. Can family ownership affect Form 5472?

Yes. U.S. constructive ownership rules can attribute certain ownership interests between family members and through entities. This can affect whether a person is treated as meeting the relevant ownership threshold.

5. Does each foreign related party require a separate Form 5472?

Generally, a reporting corporation files a separate Form 5472 for each related party with which it had reportable transactions during the tax year. This makes identifying the complete related-party network particularly important for businesses belonging to larger international groups.

6. What are the penalites for not filing Form 5472?

Standard penalties are $25,000 per year, per form.

Review the Structure Before Filing

For Hong Kong businesses operating in the United States, Form 5472 compliance should not begin and end with the direct shareholder.

If you have questions about Form 5472 reporting for a Hong Kong-owned U.S. business, OLN’s US Tax Advisory Services team can help assess your ownership structure, related-party relationships, and U.S. reporting obligations. Contact us for guidance.

Disclaimer: This article is for reference only. Nothing herein shall be construed as Hong Kong legal advice or any legal advice for that matter to any person. Oldham, Li & Nie shall not be held liable for any loss and/or damage incurred by any person acting as a result of the materials contained in this article.

Filed Under: US Tax Advisory Services, Tax Advisory Tagged With: Cross Border, Investment

Investing in the U.S.: What Hong Kong Families Should Know

October 6, 2026 by serena

For Hong Kong families, investing in the United States can provide access to attractive markets, diversification opportunities, and long-term wealth-building potential. But before capital is committed, it is important to consider how the investment will be owned and managed. The legal and tax structure chosen at the outset can significantly affect U.S. taxation, reporting obligations, liability, succession planning, and future flexibility.

For families and investors based in Hong Kong, a U.S. investment is rarely just a question of identifying the right asset. Whether the opportunity involves real estate, an operating business, private equity, or an investment portfolio, the way the investment is structured can be just as important as the investment itself.

This is particularly relevant for families whose assets, businesses, and family members may span Hong Kong, the United States, Mainland China, and other jurisdictions.

Decisions made before a transaction closes can have consequences for years – or even generations. A structure that appears straightforward today could create unexpected tax exposure, administrative requirements, or succession challenges later.

Start With the Ownership Strategy

There is no single structure that works for every investor entering the U.S. market. The appropriate approach depends on the investor’s circumstances, objectives, existing holdings, and connections to different jurisdictions.

Before selecting an entity or ownership arrangement, families should generally consider factors such as:

  • Hong Kong and other relevant tax residency considerations
  • The type and purpose of the U.S. investment
  • Long-term family and succession objectives
  • Potential exposure to U.S. estate tax
  • Existing trusts, companies, or family holding structures
  • Financing arrangements
  • The location and residency of family members and beneficiaries
  • Plans to sell, transfer, or pass the investment to future generations

These considerations are interconnected. A structure that is efficient for one family may be unnecessarily complicated – or potentially disadvantageous – for another.

Common Ways to Structure U.S. Investments

1. Limited Liability Companies (LLCs)

LLCs are frequently considered when international investors acquire U.S. assets or establish business operations. Depending on the circumstances, they can provide liability protection, management flexibility, and relatively straightforward ownership arrangements.

However, Hong Kong investors should not consider the U.S. treatment of an LLC in isolation. The way an entity is characterized and treated in other relevant jurisdictions may differ from its treatment under U.S. law.

This becomes particularly important for internationally mobile families or those with assets and family members in several countries. The analysis should therefore consider the broader cross-border implications before an LLC is established.

2. Corporations

A corporation may be appropriate for certain U.S. business investments, particularly where a company expects to grow, bring in additional investors, or establish substantial operations.

Corporate structures can offer practical advantages from an operational and governance perspective, but they may also introduce additional tax and compliance considerations.

Hong Kong investors should therefore evaluate the benefits of a corporate structure in the context of both the U.S. investment and their wider international arrangements.

3. Trusts

Trusts can play an important role for Hong Kong families concerned with preserving and transferring wealth across generations.

Depending on the family’s circumstances and applicable laws, trusts may support succession planning, asset protection, family governance, and estate planning objectives.

For Hong Kong families with beneficiaries, trustees, settlors, or assets located in different jurisdictions, however, trust planning can become particularly complex. U.S. rules governing trusts may interact with the family’s existing structures and the laws of other jurisdictions in ways that are not immediately apparent. This may be true even if the U.S. involvement is by beneficiaries that do not yet have transactions with the trust.

4. Partnerships and Joint Ventures

Partnership and joint venture arrangements can be useful when several family members, investors, or business partners want to participate in the same U.S. opportunity.

This may be particularly relevant to Hong Kong investors pursuing U.S. real estate, private business, or other investment opportunities alongside family members or investment partners.

These structures can offer considerable flexibility, but issues such as management authority, allocation of profits and losses, reporting responsibilities, transfer rights, and exit provisions should generally be addressed from the outset.

Don’t Underestimate U.S. Compliance Requirements

Completing the investment is only the beginning. Once an investor owns assets or conducts business in the United States, a range of U.S. reporting and compliance obligations may apply.

Depending on the structure and circumstances, these can include:

  • U.S. federal income tax returns
  • State-level tax filings
  • Information reporting requirements
  • Applicable ownership or disclosure requirements
  • Trust-related reporting
  • Entity filings and maintenance
  • Other cross-border reporting obligations

Missing an applicable filing can result in penalties, additional professional costs, and unnecessary administrative difficulties.

A common challenge for international families is that their advisors may be located in different jurisdictions. A Hong Kong accountant, U.S. attorney, wealth advisor, trustee, and other professionals may each be providing advice from a different perspective.

Each recommendation may make sense independently while creating unintended consequences when combined with the family’s wider international structure.

Coordinating Hong Kong and U.S. Planning

For Hong Kong families investing in the United States, coordination between advisors can be particularly important.

A typical transaction may involve U.S. attorneys and accountants alongside Hong Kong legal, tax, trust, banking, or wealth management professionals. Families with connections to additional jurisdictions may require an even broader advisory team.

For example, an ownership structure selected for a U.S. real estate investment could affect the family’s estate planning. Financing arrangements could influence how an investment is held or eventually transferred. An existing family trust or holding company could create considerations that would not arise for an individual investor.

When these issues are identified before a transaction is completed, families generally have more options for addressing them. Discovering them after closing can make restructuring considerably more difficult and expensive.

Why Planning Before the Investment Matters

Ideally, cross-border planning should begin before purchase agreements are finalized, entities are established, or investment funds are transferred from Hong Kong or elsewhere.

Early planning gives families an opportunity to consider the investment from several perspectives at once. It can help them:

  • Choose an appropriate ownership structure
  • Identify potential U.S. and cross-border tax consequences
  • Coordinate personal, family, and business objectives
  • Prepare for ongoing U.S. reporting and compliance
  • Understand relevant options considering the U.S. and Hong Kong do not have a Tax Treaty
  • Integrate the investment with existing family structures
  • Reduce unnecessary administrative complexity
  • Preserve flexibility for a future sale, transfer, or succession

The objective is not simply to complete a U.S. transaction efficiently. It is to establish a framework that continues to make sense as the investment -and the family’s circumstances – evolve.

Think Beyond the Initial U.S. Investment

For many Hong Kong families, an investment in the United States forms part of a much broader international wealth strategy.

A U.S. property acquisition may eventually become part of a family’s long-term investment portfolio. An initial business investment could lead to additional U.S. operations or acquisitions. A trust or holding structure established today may influence how wealth is managed and transferred to the next generation.

International mobility also matters. Children may study or live in the United States, family members may relocate, and business interests may expand into new jurisdictions. Changes of this kind can affect planning assumptions that were appropriate when an investment was first made.

Effective cross-border planning therefore looks beyond the immediate transaction.

Families should consider how a prospective U.S. investment fits with their existing assets, business interests, family arrangements, succession objectives, and overall global footprint.

Frequently Asked Questions for Hong Kong Investors

1. What is the best structure for a Hong Kong investor buying assets in the U.S.?

There is no universally preferable structure. The appropriate choice depends on factors including the nature of the investment, the investor’s tax residence, existing companies or trusts, financing requirements, succession objectives, and the jurisdictions with which the family has connections, and keeping in mind there is no Tax Treaty between the U.S. and Hong Kong.

2. Should a Hong Kong family use an LLC or a trust for a U.S. investment?

The two structures serve different purposes. An LLC may be useful for liability protection, management, and ownership flexibility, while a trust may have a greater role in succession, wealth preservation, and estate planning. Depending on the circumstances, more than one entity or structure may form part of the overall arrangement.

3. Do Hong Kong investors have U.S. tax and reporting obligations?

Potentially, yes. The requirements depend on the type of investment, ownership structure, activities conducted in the United States, and other circumstances. Obligations can include federal and state tax filings, information returns, trust reporting, entity filings, and other applicable disclosures. Additionally, without a proper structure, U.S. assets could be subject ot the estate tax.

4. Why should Hong Kong investors plan before transferring funds to the U.S.?

Decisions about ownership and structure can be considerably easier to implement before an investment is completed. Reviewing the U.S. tax, legal, succession, and compliance implications in advance can help avoid unnecessary restructuring and preserve greater flexibility later.

5. Why is cross-border coordination particularly important for Hong Kong families?

Hong Kong families may have assets, companies, trusts, beneficiaries, or family members across several jurisdictions. A decision that works well from a U.S. perspective may have different consequences elsewhere. Coordinating U.S. and Hong Kong advisors – and advisors in any other relevant jurisdictions – helps ensure that the investment is considered as part of the family’s overall wealth and succession strategy. OLN has a dedicated US Tax Advisory Services practice in Hong Kong. Contact us for guidance.

Disclaimer: This article is for reference only. Nothing herein shall be construed as Hong Kong legal advice or any legal advice for that matter to any person. Oldham, Li & Nie shall not be held liable for any loss and/or damage incurred by any person acting as a result of the materials contained in this article.

Filed Under: US Tax Advisory Services, Tax Advisory Tagged With: Cross Border, Investment

Oldham, Li & Nie Advises on an Award-Winning Deal

March 8, 2023 by OLN Marketing

Oldham, Li & Nie has advised on the deal ESR purchase of logistics assets from DLJ which has been recognised by the China Business Law Journal (CBLJ) as one of the “Deals of the Year 2022” in the category “Cross-border deals”.

The deal relates to the purchase by ESR, the largest real estate manager in the Asia-Pacific, of an 11-asset portfolio from US-based DLJ Real Estate Capital Partners for RMB4.4 billion (USD656 million).

The portfolio, consisting of logistics and industrial assets spanning 550,000 square metres of gross floor area cross the Yangtze River Delta ‒ including Shanghai, Kunshan, Suzhou, Taicang and Hangzhou ‒ is the largest of its kind sold in the “greater Shanghai” area.

Oldham Li & Nie acted as Hong Kong legal counsel to ESR, the deal was led by our Consultant Cermain Cheung and Associate Phyllis Wong.

Learn more about the winning deals – https://law.asia/deals-china-2022/

About China Business Law Journal

China Business Law Journal is a fully bilingual (simplified Chinese and English) monthly magazine for China-focused business and legal practitioners. CBLJ selects the deals of the years that stand out for their “overall significance, complexity, innovative nature and deal size”.

Filed Under: OLN, News, Corporate and Commercial Law, China Practice Tagged With: Corporate law, Cross Border, Business Law, Deal of the Year, CBLJ, China Business

Primary Sidebar

This website uses cookies to optimise your experience and to collect information to customise content. By closing this banner, clicking a link or continuing to browse otherwise, you agree to the use of cookies. Please read the cookies section of our Privacy Policy to learn more. Learn more

Footer

OLN logo

Suite 503, 5/F, St. George's Building 2 Ice House Street, Central, Hong Kong

Tel. +852 2868 0696 | Email us
About People Offices OLN IP Services Privacy Policy
Practice Areas Insights Careers OLN Online
About Practice Areas People Insights Offices
Careers OLN IP Services OLN Online Privacy Policy Home
linkedin twitter facebook
OLN logo

© 2026 Oldham, Li & Nie. All Rights Reserved.

Manage Consent
To provide the best experiences, we use technologies like cookies to store and/or access device information. Consenting to these technologies will allow us to process data such as browsing behavior or unique IDs on this site. Not consenting or withdrawing consent, may adversely affect certain features and functions.
Functional Always active
The technical storage or access is strictly necessary for the legitimate purpose of enabling the use of a specific service explicitly requested by the subscriber or user, or for the sole purpose of carrying out the transmission of a communication over an electronic communications network.
Preferences
The technical storage or access is necessary for the legitimate purpose of storing preferences that are not requested by the subscriber or user.
Statistics
The technical storage or access that is used exclusively for statistical purposes. The technical storage or access that is used exclusively for anonymous statistical purposes. Without a subpoena, voluntary compliance on the part of your Internet Service Provider, or additional records from a third party, information stored or retrieved for this purpose alone cannot usually be used to identify you.
Marketing
The technical storage or access is required to create user profiles to send advertising, or to track the user on a website or across several websites for similar marketing purposes.
  • Manage options
  • Manage services
  • Manage {vendor_count} vendors
  • Read more about these purposes
View preferences
  • {title}
  • {title}
  • {title}
Contact Us

Please share the details of your message here.
We will be in touch shortly.

    x