• Skip to primary navigation
  • Skip to main content
  • Skip to primary sidebar
  • Skip to footer
location iconSuite 503, 5/F, St. George's Building, 2 Ice House Street, Central, Hong Kongphone-icon +852 2868 0696 linkedintwitterfacebook
OLN IP Services
close-btn
OLN IP Services
Get bespoke and commercially-driven advice to your Intellectual Property
Learn More
OLN IP Services
OLN Online
close-btn
OLN Online
Powered by Oldham, Li & Nie, the law firm of choice for Hong Kong’s vibrant startup and SME community, OLN Online is a forward-looking and seamless addition to traditional legal services – a true disruptor.
Learn More
OLN IP Services
OLN CS
close-btn
OLN CS
OLN was established in 1987 by Gordon Oldham with the goal of providing both quality legal advice and practical legal solutions to the business community.
Learn More
OLN CS Services
  • IT
    • ENG
    • 简
    • 繁
    • FR
    • 日本語
Oldham, Li & Nie
OLN IP Services
close-btn
OLN IP Services
Get bespoke and commercially-driven advice to your Intellectual Property
Learn More
OLN IP Services
OLN Online
OLN CS
close-btn
OLN Online
Powered by Oldham, Li & Nie, the law firm of choice for Hong Kong’s vibrant startup and SME community, OLN Online is a forward-looking and seamless addition to traditional legal services – a true disruptor.
Learn More
OLN IP Services
  • Chi Siamo
    • Premi e Riconoscimenti
    • Impegno verso la Comunità
  • Persone
  • Aree di Attività
  • Insights
  • Sedi

Suite 503, St. George's Building,
2 Ice House Street, Central, Hong Kong

Tel. +852 2868 0696 | Send Email
linkedin twitter facebook
OLN Blue

OLN Law

  • Aree di Attività
  • Awards and Rankings
  • Block Content Examples
  • Careers
  • Chi Siamo
    • Corporate Social Responsibility
    • Premi e Riconoscimenti
  • Client Information & Registration
  • Contact Us
  • Cookie Policy (EU)
  • Globalaw
  • Oldham, Li & Nie
  • OLN Podcasts
  • Persone
  • Privacy Policy
  • Review
  • Reviews
  • Sedi
  • Standard Terms of Engagement
  • Chi Siamo
    • Premi e Riconoscimenti
    • Impegno verso la Comunità
  • Persone
  • Aree di Attività
  • Insights
  • Sedi

The End of the “418 Rule”: What Employers in Hong Kong Need to Know About the New “417/468” Continuous Contract Requirement

OLN Marketing

The End of the “418 Rule”: What Employers in Hong Kong Need to Know About the New “417/468” Continuous Contract Requirement

11 Settembre 2026 by OLN Marketing

Introduction

For decades, whether an employee was regarded as employed under a “continuous contract” under the Employment Ordinance (Cap. 57) (“EO”) depended on the “418 rule”: the employee had to be employed continuously by the same employer for four weeks or more and work at least 18 hours in each week. Continuous contract status matters because it is the gateway to important statutory protections and benefits, including paid annual leave, statutory holiday pay, sickness allowance, maternity and paternity leave, severance payment and long service payment.

With effect from 18 January 2026, the “418 rule” has been replaced by a more flexible “417/468” framework. Under the new requirement, an employee will be regarded as employed under a “continuous contract” if they have been employed continuously by the same employer for four weeks or more and either: (i) worked at least 17 hours in each week; or (ii) where they worked less than 17 hours in any week, worked 68 hours or more in the four-week period comprising that week and the three weeks immediately preceding it. This article explains the new threshold, why the rolling four-week calculation matters, and which industries and working arrangements are likely to be most affected.

“Continuous Contract”

The practical concept and threshold of a “continuous contract” is fundamental to Hong Kong employment law. By virtue of satisfying this threshold, employees access a broad array of statutory protections and entitlements, subject in each case to the employee satisfying the applicable eligibility conditions for that particular benefit, including:-

  • Annual leave and statutory holidays;
  • Sickness allowance and maternity/paternity leave;
  • Severance payment and long service payment; and
  • Protection against unreasonable dismissal.

The New “Continuous Contract” Threshold: From “418” to “417/468”

A comparison of the old and new requirements is as follows:-

Definition of “continuous contract” under “418 rule”
(effective before 18 January 2026)
Definition of “continuous contract” under new “417/468 rule”
(effective on or after 18 January 2026)
Employee works 18 or more hours per week for four consecutive weeks.Employee works at least 17 hours in each week for four or more consecutive weeks; OR 
Where the employee works less than 17 hours in any week, the employee works 68 hours or more in the four-week period comprising that week and the three weeks immediately preceding that week. The 468 limb does not apply during the first three weeks of a new employment.

In particular, under “468 rule”, rather than measuring hours on a week-by-week basis, it looks at an employee’s aggregate working hours across a rolling four-week window. This makes it far harder for employers to sidestep the threshold by varying rosters from week to week. For illustration, an employee whose hours fluctuate between 10 and 22 hours per week may well qualify, even if they never consistently exceed 17 hours in any given week.

In particular, the “468 rule” is significant because it moves the analysis beyond a simple week-by-week threshold. Where an employee works less than 17 hours in a given week, employers must look at the employee’s aggregate working hours across that week and the three immediately preceding weeks. This makes fluctuating rosters more important: a shorter week will not necessarily prevent continuous contract status if the rolling four-week total reaches 68 hours, although the assessment remains fact-sensitive and the 468 limb will not assist during the first three weeks of a new employment.

Crucially, under section 3(2) of the EO, the burden of proving that an employment contract is not a continuous contract lies with the employer in the event of a dispute.

Impact on the Employment Landscape

The practical ramifications of this amendment are significant and broad-reaching.

Part-time, casual, seasonal and variable-hours workers are likely to be the primary beneficiaries. The sectors most directly affected are those with heavy reliance on shift-based or fluctuating staffing, including retail, catering, hospitality, food and beverage, entertainment, logistics, events and promotional work. Platform or gig-style arrangements may also require closer review where the underlying relationship is, in substance, employment rather than genuine self-employment.

Meanwhile, employers face a corresponding increase in compliance and administration obligations. Businesses that previously relied on the 18-hour weekly threshold, or rostered staff close to that threshold, should reassess their workforce structures, contracts, payroll rules and timekeeping systems. Key areas of review include:-

  • Employees newly qualifying as continuous contract employees may become entitled to statutory benefits, requiring payroll and benefits recalculation.
  • Employment contracts, staff handbooks and rostering policies that refer to the old “418 rule” or assume a fixed 18-hour weekly threshold should be reviewed and updated.
  • Given the combined “417/468” framework, employers should track both weekly hours and rolling four-week totals, and maintain robust timekeeping and payroll records to determine eligibility and support the employer’s position in any dispute.
  • Severance and long service exposure: As more workers qualify as continuous contract employees, employer exposure to severance payment and long service payment claims, as well as holiday, sickness and leave-related costs, may increase.

How can OLN help?

The replacement of the “418 rule” with the new “417/468” continuous contract requirement represents one of the most significant expansions of statutory employment protection in Hong Kong in recent years. For businesses with part-time, casual, seasonal, event-based or variable-hours staff, the implications are immediate and wide-ranging.

Our team at OLN can assist with workforce audits to identify employees who now qualify, or may soon qualify, as continuous contract employees; review and update employment contracts, staff handbooks and rostering practices to reflect the new threshold; and advise on statutory entitlements, payroll administration, record-keeping and dispute risk under the amended framework.

Should you have any questions, please feel free to contact us.

Disclaimer: This article is for reference only. Nothing herein shall be construed as Hong Kong legal advice or legal advice of any kind to any person. Oldham, Li & Nie shall not be held liable for any loss and/or damage incurred by any person acting as a result of the materials contained in this article.
Filed Under: Senza categoria, Employment and Business Immigration Law

The Rise of the Employer of Record in Hong Kong and How Businesses Can Leverage It

11 Settembre 2026 by OLN Marketing

Introduction

Hong Kong’s employment landscape is changing. The recent amendment to the Employment Ordinance (Cap. 57) (“EO”), which introduces a broader continuous contract threshold from 18 January 2026, is one of several developments that should prompt businesses to take a closer look at how they structure and manage their workforce. For many, that review may well lead them to an increasingly familiar solution: the Employer of Record.

The Employer of Record (“EOR”) model is not new, but its profile in Hong Kong has grown considerably in recent years. Fuelled by the rise of cross-border hiring, more flexible workforce models, and a steady expansion of statutory employment obligations, more businesses are turning to EOR arrangements to simplify the way they engage workers. The appeal is understandable. There are, however, risks that businesses should plan against.

The EOR Model

An EOR is a third-party entity that formally acts as the employer on record of workers on behalf of a client company. In a typical EOR arrangement, the EOR signs the employment contract and handles payroll, MPF enrolment and contributions, employer tax reporting and other employment administration, while the client company retains day-to-day operational control over the workers’ activities.

The tripartite EOR structure is, in essence, as follows:

  • The EOR employs the workers on paper and manages agreed compliance obligations;
  • The client company directs the workers’ daily tasks and business activities; and
  • The employees are formally contracted to the EOR but functionally serve the client.

The EOR model has found particular appeal among businesses seeking to expand into new markets without the delay and cost of establishing a local entity, as well as multinationals looking to centralise employment administration across jurisdictions.

The Benefits of EOR

In light of the new continuous contract framework, EOR arrangements offer a number of practical attractions for Hong Kong businesses.

  1. The EOR can take responsibility for monitoring evolving statutory requirements and managing outsourced compliance processes so that employment contracts, payroll systems and benefits structures reflect the applicable law.
  2. Businesses can engage talent quickly, without setting up a local entity and without having to build the full local employment administration infrastructure themselves. This can reduce costs and increase efficiency.
  3. The administrative burden on internal HR departments is also reduced. Payroll calculations, MPF enrolment and contributions, employer reporting to the Inland Revenue Department (“IRD”) under the salaries tax regime, and statutory leave tracking can all handled by the EOR.
  4. Companies considering a Hong Kong presence can hire locally on a trial basis through an EOR before committing to a formal corporate structure, allowing them to conduct market testing before committing capital and labour for the long term.

Key EOR Risks to Consider

Despite its commercial appeal, the EOR model carries meaningful legal and operational risks that businesses should evaluate carefully before proceeding.

1. Risk of Being Deemed the True Employer

Under Hong Kong law, the question of who is the “employer” for the purposes of the EO may turn on the substance of the relationship, not merely the label assigned to it. The courts and tribunals may examine the reality of the arrangement. If the client company:

  • exercises substantial control over the worker’s day-to-day activities;
  • provides the worker’s equipment, workspace, and tools;
  • integrates the worker into its own organisational structure; or
  • fails to maintain a meaningful distinction between its own staff and the EOR-engaged worker,

there is a risk that the client company may be found to be the worker’s true employer, depending on the facts, notwithstanding the contractual position with the EOR. This could expose the client to EO-related liabilities, including obligations relating to severance payment, statutory holiday pay, annual leave, sickness allowance and claims for unreasonable dismissal.

2. Employment Agency Regulations

The EOR model, if not properly structured, may also raise employment agency licensing issues. Employment agencies are regulated under the  EO and the Employment Agency Regulations (Cap. 57A), and employment agencies must generally be licensed by the Labour Department. An EOR that functions essentially as a broker, by introducing or placing workers with client companies without genuinely acting as the substantive employer, may risk being treated as an unlicensed employment agency, with attendant regulatory and criminal exposure.

3. MPF and Salaries Tax Obligations

Even where an EOR arrangement is properly structured, client companies should satisfy themselves that the EOR is enrolling eligible employees in an MPF scheme within the statutory framework, making timely and correct MPF contributions, and filing accurate employer returns and related IR56 forms with the IRD. The statutory obligation to make MPF contributions sits with the employer of record, but reputational and operational risks can flow back to the client if an EOR defaults on these obligations.

4. Permanent Establishment Risk

For overseas companies engaging workers in Hong Kong through an EOR, there may also be Hong Kong profits tax risk if the worker’s activities constitute a permanent establishment in Hong Kong or otherwise result in Hong Kong sourced profit for Profits Tax purposes, particularly if they involve entering into contracts on the company’s behalf. Businesses should take advice on this risk before deploying an EOR arrangement, particularly where the engaged workers exercise significant commercial discretion.

5. Continuity of Employment and the “417/468 Rule”

Under the new framework, businesses that rotate EOR-engaged workers through consecutive contracts must be vigilant. From 18 January 2026, an employee is regarded as employed under a continuous contract if the employee has been continuously employed by the same employer for four weeks or more and either works at least 17 hours in each week or, where the employee works less than 17 hours in a week, has worked 68 hours or more in the four-week period comprising that week and the preceding three weeks. The “468 Rule” does not apply to the first three weeks of a new employment, and attempts to structure arrangements to avoid statutory entitlements may create additional legal and reputational risk.

How can OLN help?

OLN has extensive experience advising businesses, from market entrants to established multinationals, on the full spectrum of employment issues in Hong Kong. Whether you are considering an EOR arrangement for the first time, reviewing an existing structure for compliance risk, or navigating the implications of the new continuous contract framework, our team can help you assess your exposure and structure your workforce arrangements on a sound legal footing.

Should you have any questions, please feel free to contact us.

Disclaimer: This article is for reference only. Nothing herein shall be construed as Hong Kong legal advice or legal advice of any kind to any person. Oldham, Li & Nie shall not be held liable for any loss and/or damage incurred by any person acting as a result of the materials contained in this article.

Filed Under: Senza categoria, Employment and Business Immigration Law

Hong Kong Succession Guide – What Happens to Hong Kong Assets When a Mainland Entrepreneur Passes Away

3 Settembre 2026 by OLN Marketing

When a mainland Chinese entrepreneur dies, leaving assets in the Hong Kong SAR, the assets do not automatically transfer to family members. The Hong Kong SAR has its own legal system and probate process, which must be followed before assets can be accessed or distributed to the deceased’s heirs. This article briefly explains the Hong Kong SAR legal process to distribute a deceased’s assets.

First step: Are there assets in Hong Kong?

The first step would be to determine which assets fall within the legal jurisdiction of the Hong Kong SAR. These assets may include bank accounts held with Hong Kong banking institutions, shares held in Hong Kong companies, real property (real estate) held in Hong Kong and/or securities traded on the Hong Kong Stock Exchange. The administration of the above types of assets would be dealt with through the Hong Kong court process and Hong Kong law will generally govern Hong Kong real estate, regardless of the deceased’s nationality or place of residence.

The legal authority to deal with the deceased’s Hong Kong assets is granted by the High Court of Hong Kong either in the form of a grant of probate (if the deceased left a valid will naming an executor who is willing to act) or a type of letters of administration, if the deceased left no will, the will is invalid or no executor is able to act.

Did the deceased leave a will?

If the deceased left a will, the Hong Kong court will need to decide whether the will is valid under Hong Kong law and whether it covers Hong Kong assets. Hong Kong recognises wills executed in accordance with the law of the place of execution or the deceased’s domicile. If the will was executed in the People’s Republic of China (“PRC”), issues that sometimes arise include the differences in formal requirements between the two jurisdictions, lack of clarity over asset coverage and the absence of an appointed executor. If an executor is named in the will, the executor (usually with the help of his/her Hong Kong solicitor) applies for probate in Hong Kong.

What if the deceased left no will or an invalid will?

If the deceased left no will or an invalid will, this is deemed an intestacy and the deceased’s estate will be distributed in accordance with Hong Kong’s intestacy rules pursuant to the Intestates’ Estates Ordinance Cap 73.

Who are the heirs in an intestacy?

Very broadly speaking, the surviving spouse (with a fixed statutory legacy in specific situations) and children take priority and extended family members such as parents and siblings inherit only if closer relatives do not exist.  A suitable family member (often the surviving spouse or an adult child) applies for Letters of Administration in order to administer the estate.

What are the documents generally required of PRC heirs?

PRC heirs are typically required to present the following documentation – death certificate issued by mainland Chinese authorities, resident identity cards of the deceased and heirs, hukou registration records to prove family relationships, marriage or divorce documents if applicable and notarial certificates confirming identity and kinship. In practice, Hong Kong courts usually require these documents to be notarised by a notary public in the PRC and properly authenticated (for example, via current apostille/legalisation arrangements).

What if probate proceedings have already been completed in the PRC?

Even if probate proceedings have already been completed in the PRC, it is not possible to apply for recognition of these probate documents in Hong Kong. Unfortunately the PRC is not listed as a country under Hong Kong’s statutory resealing regime as the listed countries are all common law regimes. A fresh application in Hong Kong is required.

Are there estate duties and estate taxes in Hong Kong?

Estate duties have been abolished in Hong Kong for deaths occurring after 11 February 2006 and there have never been estate or inheritance taxes. However, tax issues may arise in the PRC and other applicable jurisdictions.

What are some practical challenges faced by PRC heirs?

As a result of the numerous complications mentioned above, some common challenges faced by PRC heirs include delays due to incomplete documentation, difficulty proving family relationships where hukou registration records differ from actual family relationships, translation (from Chinese to English) as well as notarisation requirements and disputes over the validity or interpretation of wills (the latter complication is not unique to PRC heirs but occurs across all jurisdictions).

It is important to note that if the deceased was domiciled in the PRC, PRC succession law may be relevant in deciding who inherits movable assets in Hong Kong, although the Hong Kong court issues the grant and supervises the administration.

What is the expected timeline?

A straightforward probate application in Hong Kong takes a few months to complete. Complex cross-border estates take longer, particularly where there is no will, documents must be obtained from mainland authorities and/or heirs are in dispute about their entitlements.

Does planning ahead help?

For PRC citizens with assets in Hong Kong, advance planning can significantly reduce complications in the probate process. Many have opted to execute separate Hong Kong wills to cover their Hong Kong assets to streamline the legal process in Hong Kong, appointed executors familiar with Hong Kong laws and maintained clear records of bank accounts, shareholdings, property and other assets.

Conclusion

The passing of a loved one is one of the most difficult times in a person’s life. With the benefit of advance legal planning, heirs will be able to navigate the complicated process of probate more smoothly and avoid unnecessary stress during a time of immense grief. And with a properly drafted will, one can generally choose who should inherit one’s assets, without regard to fixed intestacy rules in Hong Kong.

In conclusion, it is advisable to seek professional legal advice if one’s estate involves Hong Kong assets.

Disclaimer: This article is for reference only. Nothing herein shall be construed as Hong Kong legal advice or any legal advice for that matter to any person. Oldham, Li & Nie shall not be held liable for any loss and/or damage incurred by any person acting as a result of the materials contained in this article.

Filed Under: Senza categoria, Elder Law Practice Group, Private Client – Estate Planning & Probate Tagged With: Estate planning

Reproductive Technology in Hong Kong – Legal Framework, Ethics and Emerging Judicial Trends

24 Agosto 2026 by OLN Marketing


(This article was published in the August 2026 Issue of the Hong Kong Lawyer)

Introduction

Louise Joy Brown, born in Manchester on 25 July 1978, was the world’s first baby conceived via in vitro fertilisation (“IVF”). Eight years later, Hong Kong’s first IVF baby was born in December 1986 at a private hospital in Happy Valley. His birth at the time was so controversial that his parents declined to reveal his and their identities, as well as his birthdate. As reported in the South China Morning Post, the Catholic Church had condemned the procedure as “an artificial manoeuvre to create life”.

Today it is estimated that 57 IVF babies are born every hour globally. Technological advancements over the years have rendered IVF procedures more mainstream, safer and success rates much higher.

Meanwhile in Hong Kong, the total fertility rate has been below the replacement level of 2.1 for decades, and even plunged to a record low in 2025. The HKSAR government’s recent efforts to reverse this trend include a one-off cash allowance of $20,000 for babies born between 25 October 2023 – 24 October 2026, increased child tax allowance, a “families with newborns allocation priority scheme” for public housing, increased childcare centres, increased quota for  IVF treatment within the public medical system and a new tax deduction for medical expenses related to assisted reproductive services.

In December 2025, the Human Reproductive Technology (Licensing) (Amendment) Regulation 2025 L.N. 160 of 2025 removed the previous 10-year statutory limit on own-use gamete and embryo storage. This is a significant change that aligns with modern international norms and advances reproductive autonomy.

Another area of reform that has been debated is updating the Human Reproductive Technology Ordinance, Cap 561 (“HRTO”). Enacted in 2000, the HRTO is the principal legislation that governs human reproductive technology (“RT”) procedures in Hong Kong. The HRTO at present effectively ringfences access to RT procedures (other than egg freezing) to “parties to a marriage”. Same sex marriage is not yet recognised under Hong Kong laws, leaving access to infertile, married heterosexual couples. Commercial surrogacy is also prohibited under the HRTO.

Principal Legislation

The HRTO preamble states that it is an ordinance “to regulate reproductive technology procedures, and the use, for research and other purposes, of embryos and gametes; to confine the provision of reproductive technology procedures to infertile couples subject to any express provision to the contrary in any code; to regulate surrogacy arrangements; to establish a Council on Human Reproductive Technology; and to provide for matters incidental thereto or connected therewith”.

Regulatory Body and Licensing

Pursuant to the HRTO, s.5, the Council on Human Reproductive Technology (“CHRT”) is the statutory body charged with a number of statutory functions under the HRTO, including licensing and policy-related duties..

Definitions

Reproductive technology procedures are defined in the HRTO as,

“…a medical, surgical, obstetric or other procedure (whether or not it is provided to the public or a section of the public) assisting or otherwise bringing about human reproduction by artificial means, and includes—

(a) in vitro fertilization;

(b) artificial insemination;

(c) the obtaining of gametes;

(d) manipulation of embryos or gametes outside the body;

(e) a procedure specified in a notice under subsection (2)(a)(ii) to be a reproductive technology procedure; and

(f) a gender selection achieved or intended to be achieved by means of a procedure which falls within this definition,

but excludes a procedure specified in a notice under subsection (2)(b)(ii) not to be a reproductive technology procedure;”.

The HRTO does not define infertility. There is a general reference in the preamble to confining reproductive technology procedures to infertile couples. The World Health Organization defines infertility as “a disease of the male or female reproductive system defined by the failure to achieve a pregnancy after 12 months or more of regular unprotected sexual intercourse” and this is a generally accepted definition for practical purposes.

Code of Practice and Professional Standards

Pursuant to the HRTO, s.8, the CHRT shall issue and maintain a Code of Practice on Reproductive Technology and Embryo Research (“Code”), which sets out detailed guidelines for RT service providers and embryo researchers. The Code first came into effect on 1 August 2007. 

The preamble of the Code states that while it provides guidance and minimum standards to safeguard the health and interests of service users and to protect the welfare of children born via RT, professionals concerned should still follow the codes of practice and professional ethics of their own disciplines, which the Code does not supersede.

Eligibility

The HRTO, s.15(5) restricts RT procedures being provided to persons who are parties to a marriage. Read in conjunction with the preamble to the HRTO and the Code paragraph 4.2 which refer specifically to infertile couples, in general only infertile married couples are treated in practice as able to avail themselves of RT procedures except this shall not apply to surrogate mothers pursuant to section 15(6) or couples who are permitted to use embryo sex selection for medical conditions e.g., to avoid serious sex linked diseases, pursuant to section 15(3) and as specified in Schedule 2 of the HRTO.

Since the preamble of the HRTO and Chapter IV of the Code state that RT procedures should only be made available to infertile couples, RT procedures for social or non medical reasons are not generally permitted except in very limited circumstances.

Specific Exclusions and Exceptions

Single persons, cohabiting heterosexuals who are not married and same sex couples are not eligible to receive RT procedures as the HRTO generally limits treatment to persons who are parties to a marriage as interpreted under current laws (the Code paragraph 4.1 note 12).

Within that framework, the HRTO allows for narrowly defined exceptions such as under section 15(7) which allows the continuation of an RT procedure where the couple was married at the time gametes or an embryo were first placed in the woman’s body, even if the marriage has subsequently ended. Another example is embryo sex selection to avoid serious sex linked diseases. Schedule 2 (and its amendment) of the HRTO specifies the sex linked diseases for which embryo sex selection is permitted.

While it appears that those who are legally allowed to avail themselves of RT procedures in Hong Kong are adequately protected and supported, those who do not fit within the current legal framework (such as singles, unmarried heterosexual couples, same sex couples) remain effectively excluded, regardless of their reproductive circumstances and Hong Kong’s alarming birth rate.

​The HRTO and the Code restrict the provision of RT procedures, in general, to infertile, married heterosexual couples. Same sex couples and single persons are excluded from the vast majority of RT procedures under current legislation.

Commercial transactions in (the buying and selling of) embryos, gametes and surrogacy are prohibited. Hence, only altruistic donations of embryos, gametes and surrogacy arrangements are permitted although reimbursement of legitimate expenses is allowed, in accordance with the HRTO, s.16 and s.17. Appendix II of the Code sets out guidelines on reimbursing donors.

Emerging Judicial Trends

While legislation has been updated at a slow pace, case law sits at the intersection of law, evolving ethics and current public policy. In Re A and Another HKCFI 1749; 5 HKLRD 366 (HCMP 1571/2018, Au-Yeung J, 14 October 2019), the court had extended the statutory 6 month time limit in the Parent and Child Ordinance Cap 429 s.12(2) and retrospectively approved commercial surrogacy payments despite the illegality of commercial surrogacy arrangements in Hong Kong because 1) the applicants acted in good faith without moral taint or intent to defraud, 2) the payments were not so disproportionate as to offend public policy and 3) the A & B v E ** HKCFI 3143** (HCMP 731/2023…) parental order was in the best interests of the children vis-a-vis their lifelong welfare and legal identity. Au-Yeung J applied and elaborated the same analytical framework in A & B v E HKCFI 3143 (HCMP 731/2023, Au-Yeung J, 4 December 2023).

The above two cases, together with CS v SW HKCFI 2326 (HCMP 1731/2023, Au-Yeung J, 25 September 2024) and HSC v T; HSC v D HKCFI 770 (HCMP 706–707/2025, Au-Yeung J, 2 February 2026) form an emerging body of case law that points to Hong Kong courts granting parental orders and approving commercial surrogacy payments made in good faith, always with an overriding concern for the lifelong welfare of the child. In the latter case, the court again granted parental orders and approved separate commercial surrogacy payments for two oral surrogacy arrangements made in Shenzhen with two surrogates and extended the deadline of the statutory 6 month time limit in the Parent and Child Ordinance Cap 429, s.12(2). The lifelong best interests of the two children were considered. Rather than deliberately committing a breach, the commissioning parents had unfortunately acted without obtaining proper legal advice and had been ignorant of the law.

Surrogacy and Legal Parenthood

Surrogacy arrangements fall within the purview of the HRTO. The preamble of the HRTO sets out its mandate to “to confine the provision of reproductive technology procedures to infertile couples subject to any express provision to the contrary in any code”. Pursuant to the Code paragraph 12.2(b), a RT procedure may only be provided if the wife in that marriage is unable to carry a pregnancy to term and no other treatment option is practicable. In accordance with the Code paragraph 12.7, counselling by a multi-disciplinary team must be provided to all parties in the surrogacy arrangement, including the husband of the surrogate, if any.

Surrogacy is only permitted in altruistic circumstances and not on a commercial basis. Pursuant to the HRTO, s.17, there is a prohibition on surrogacy arrangements on a commercial basis. The Code paragraph 12.1 cross references the prohibition.

No surrogacy arrangement is enforceable by law under the HRTO, s.18 and as set out per the Code paragraph 12.6. As well, all parties to a surrogacy arrangement should be informed that the surrogacy arrangement is not enforceable.

The Code paragraph 12.8 sets out the suitability criteria by which commissioning couples and their surrogates must be assessed, taking into account their physical, mental and social well being. The surrogate must be at least 21 years of age (the Code paragraph 12.4).

The Parent and Child Ordinance Cap 429, s.9 states that the woman who gives birth is treated by law as the child’s mother (and if she is married and her husband has consented, he is treated by law as the child’s father) despite any surrogacy agreement that is in place. Section 12(2) prescribes that a commissioning couple must apply to the court within six months of their child’s birth for a parental order, and the court may make such a parental order provided all the conditions of subsections 12(1) – (7) have been met.

In the case of HC v WYH HKCFI 1157 (HCMC 3/2023, Chu J, 30 April 2024), the parties were married but subsequently separated. The issue before the court was whether the lack of parental orders or adoption orders (the two children in question were born out of commercial surrogacy arrangements made in California) were obstacles to the Family Court making orders in the best interests of the children as they were “children of the family”.

The court ruled that the statutory definition of “child of the family” as set out in section 2 of the Matrimonial Proceedings and Property Ordinance Cap 192 is broad and autonomous and children born of commercial surrogacy arrangements fall within the definition (without adoption or parental orders in place), giving the court jurisdiction to make custody and maintenance orders in divorce proceedings.

In the case of CS v SW HKCFI 2326, HCMP 1731/2023 (25 September 2024, Au-Yeung J), the court ruled that the children’s best interests and the need for secure lifelong legal status with their de facto parents outweighed the serious breaches of Cambodian, Thai and Hong Kong laws regarding commercial surrogacy and a delay of over 4 years beyond the statutory limit specified in the Parent and Child Ordinance Cap 429 s.12(2).

Sanctions and Enforcement

Breaching the HRTO may be a criminal matter and may lead to fines, imprisonment and regulatory sanctions including the loss of professional licences for practitioners and researchers.

Conclusion

Hong Kong’s legal framework in respect of RT was enacted a quarter century ago. The December 2025 removal of the 10-year limit on gamete and embryo storage was a welcome modernisation although the foundational framework for eligibility and access to RT remains the same.

The more significant developments have come from the judicial rather than legislative front – the four seminal cases discussed above have established that the courts will grant parental orders and approve commercial surrogacy payments made by commissioning parents where they acted in good faith (often in ignorance of their legal positions), the payment amounts were not disproportionate and the child’s best interests were taken into account.

The gap between what the HRTO prohibits and what courts have been willing to regularise is widening. Children born into this tenuous legal environment deserve legal certainty beyond what the courts have been able to grant. Hong Kong’s record low birth rate should tilt economic and social policy towards inclusive legislative reforms that follow judicial developments. Until then, those who are being denied access to RT procedures in Hong Kong will continue to search overseas for solutions.

Disclaimer: This article is for reference only. Nothing herein shall be construed as Hong Kong legal advice or any legal advice for that matter to any person. Oldham, Li & Nie shall not be held liable for any loss and/or damage incurred by any person acting as a result of the materials contained in this article.
Filed Under: Senza categoria, Elder Law Practice Group

Family Offices in Hong Kong: Tax Concessions, Re-domiciliation, and Proposed 2026 Reform

7 Luglio 2026 by OLN Marketing

Hong Kong stands out as a premier destination for family offices, offering a unique blend of business-friendly policies, robust legal frameworks, and strategic advantages.

1. Business-Friendly Tax Regime

Hong Kong imposes low and simple taxes with no VAT, capital gains, dividend, or inheritance taxes. As at June 2026, Hong Kong holds 58 comprehensive avoidance of double taxation agreements, with another 16 under negotiation.

2. Robust Legal System

The city operates under a Common Law framework, providing strong rule of law and investor protection.

3. World-Class Financial Services

As a leading global hub for private banking, asset management and professional advisory services, Hong Kong offers tailored solutions for HNWIs and families.

4. Skilled Talent Pool

Hong Kong is home to a highly skilled, multilingual workforce.

5. Government Support

The Hong Kong government actively supports family offices through initiatives like FamilyOfficeHK under InvestHK and tax concessions for single-family offices.

6. Strategic Location

Hong Kong serves as a gateway to Mainland China and the Asia-Pacific region.

Re-Domiciliation of Family Offices

As of May 2025, non-Hong Kong incorporated companies, including family offices, can re-domicile to Hong Kong under a new statutory regime. This allows family offices to relocate their operations while retaining their legal identity and continuity. The streamlined process involves an application to the Companies Registry, with approvals typically granted within two weeks.

Key highlights:

  • The family office retains all assets, rights, obligations, and legal standing post-transfer
  • The family office obtains the same rights as family offices incorporated in Hong Kong
  • A fixed application fee (HK$6,050 electronically / HK$6,725 in hard copy)
  • Upon approval, the family office becomes a Hong Kong-incorporated entity and must deregister in its original jurisdiction within 120 days

Regulatory and tax implications:

  • Tax continuity is preserved – profits tax applies only to income sourced in Hong Kong
  • Relief and credits are available to avoid double taxation during transition
  • No stamp duty is triggered by re-domiciliation

Tax Concessions for Family-owned Investment Holding Vehicles (FIHVs)

Hong Kong’s Inland Revenue (Amendment) (Tax Concessions for Family-owned Investment Holding Vehicles) Ordinance 2023 introduced a 0% profits tax concession for qualifying FIHVs.

Who qualifies:

  • ≥ 95% beneficial interest held, in aggregate, by one or more than one member of the family (charities ≤ 25%, outsiders ≤ 5%)
  • Normally managed and controlled in Hong Kong, outsourcing is permissible
  • Holds ≥ HK$240 million specified assets (shares, stocks, bonds, debentures, etc.)
  • Carries on all core income-generating activities in Hong Kong with ≥ 2 qualified full-time staff and ≥ HK$2 million local operating spend
  • Not a business undertaking

What’s covered:

  • Transaction in specified assets (qualifying transactions): trading securities, FX, private-company shares, derivatives, etc.
  • Transactions incidental to the carrying out of qualifying transactions (receipts capped at 5% of total receipts)

Practical steps to obtain tax certainty:

  1. Map ownership to confirm ≥ 95% family control (with any charity/unrelated shareholding within limits).
  2. Elect for the concession – once, in writing – before filing the first relevant tax return.
  3. Verify substance annually: head-count, spend, and asset NAV.
  4. Monitor transactions for the 5% incidental threshold and private-company anti-avoidance triggers.
  5. Maintain documentation (family tree, group chart, management agreements, NAV calculations) ready for audit or advance-ruling submission.

Legislative Update: 2026 Preferential Tax Regimes Bill

  • On 12 June 2026, Hong Kong gazetted the Inland Revenue (Amendment) (Preferential Tax Regimes for Funds, Family-owned Investment Holding Vehicles and Carried Interest) Bill 2026.
  • The Bill proposes to expand Hong Kong’s preferential tax regimes for:
    • funds;
    • Family-owned Investment Holding Vehicles;
    • carried interest.
  • Expanded qualifying asset classes
    • The 0% profits tax concession would be expanded to cover additional asset classes, including:
      • digital assets;
      • gold and other precious metals;
      • specified commodities;
      • carbon credits;
      • private credit.
  • Broader eligible fund structures
    • Eligibility would be extended beyond traditional open-ended fund structures to include:
      • certain “fund-of-one” structures;
      • wholly-owned investment vehicles;
      • pension funds;
      • charity funds.
  • Carried interest tax relief
    • The Bill would enhance tax relief for performance-linked returns, including carried interest, for private equity and venture capital funds.
    • This is intended to strengthen Hong Kong’s competitiveness as a private capital and asset management hub.
  • Removal of 5% incidental threshold
    • The existing draft memo states that the concession covers transactions in specified assets and that receipts from incidental transactions are capped at 5% of total receipts.
    • The Bill proposes to remove this 5% incidental threshold, giving family offices greater flexibility in treasury, cash management and interest-earning activities.
  • Interaction with non-tax incentives
    • Hong Kong’s Capital Investment Entrant Scheme provides a residency pathway for individuals making a qualifying HK$30 million investment, including at least HK$3 million into a government-managed investment portfolio.
    • The scheme may also allow family members to be included, facilitating relocation alongside the family office structure.

Anti-Avoidance Measures

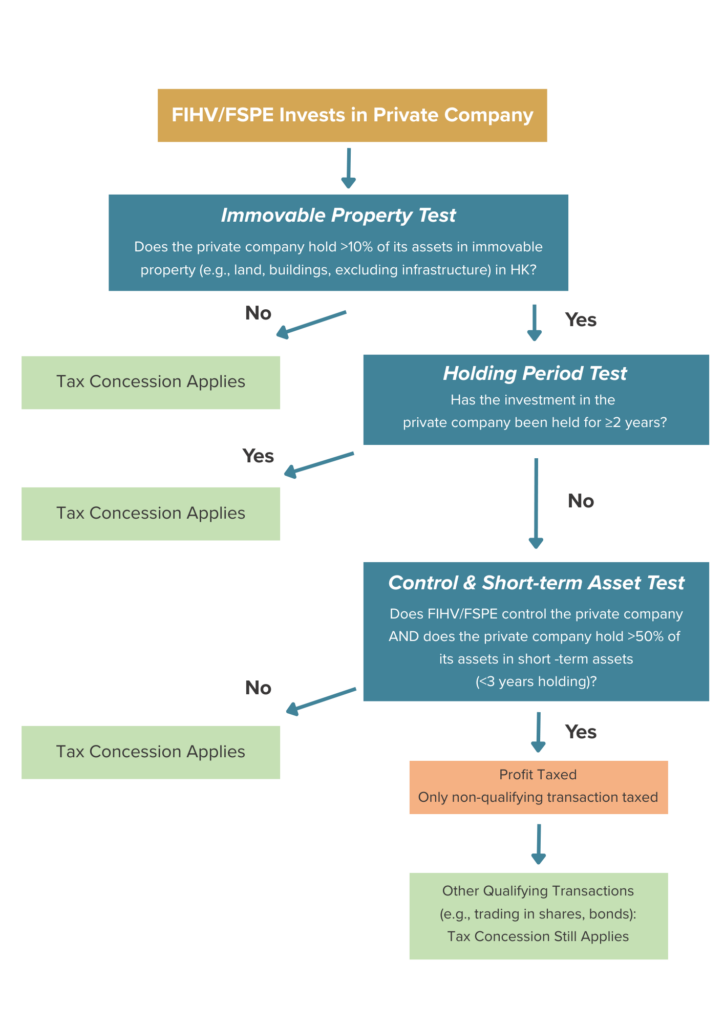
Hong Kong has implemented anti-avoidance measures to ensure that tax concessions are not abused. These measures include tests for immovable property, holding periods, and control and short-term asset tests.

Anti-Avoidance Measures

With its favourable tax regime, robust legal system, world-class financial services, skilled talent pool, and strong government support, Hong Kong is the ideal location for family office. Whether you are looking to establish a new family office or re-domicile an existing one, Hong Kong offers the perfect environment for long-term wealth planning and growth. Please contact us for further information.

Disclaimer: This article is for reference only. Nothing herein shall be construed as Hong Kong legal advice or any legal advice for that matter to any person. Oldham, Li & Nie shall not be held liable for any loss and/or damage incurred by any person acting as a result of the materials contained in this article.

Filed Under: Senza categoria, Family Office Sevices

Oldham, Li & Nie Launches Family Office Services to Support International Families in Hong Kong

6 Luglio 2026 by OLN Marketing

Oldham, Li & Nie (OLN) is pleased to announce the launch of its dedicated Family Office Services practice, expanding its capabilities in private wealth, trusts, succession planning, and cross-border structuring to meet the growing needs of international families.

Hong Kong has established itself as a premier destination for family offices, underpinned by common law system, attractive tax regime, and government-backed initiatives such as FamilyOfficeHK, tax concessions for Family-Owned Investment Holding Vehicles (FIHVs), and the New Capital Investment Entrant Scheme (New CIES). In 2026, the city has become the world’s largest cross-boundary wealth management centre, according to the Boston Consulting Groupi, reinforcing its appeal for global wealth planning,

OLN’s new Family Office Services practice will provide integrated legal support across the following areas:

  • Family Office Establishment and Structuring
  • Wills and Succession Planning
  • Trusts and Asset Protection
  • Complex Estate Planning
  • Cross-Border Tax and Structuring Advice, including the US and France elements
  • International Family Office Coordination
  • Ongoing Accounting and Reporting
  • Outsourced CFO and COO Support
  • Strategic Business Advisory Services Tailored to Family Offices and Private Investment Structures
  • Litigation Support
  • Immigration Law

“Hong Kong offers an exceptional platform for families seeking to build a lasting presence in Asia while staying closely connected to opportunities around the world,” said Gordon Oldham, Senior Partner. “At OLN, we understand that every family’s journey is unique. Drawing on our longstanding strengths across private client, tax and corporate services – as well as our dedicated US tax and French practices – we take a truly personal approach. We work alongside our clients to create tailored structures that not only protect and grow their wealth, but also reflect their values, aspirations and long-term legacy.”

The firm’s Family Office Services practice adopts a multidisciplinary approach, working closely with third-party fund managers and financial advisers.

For more information about the Family Office Services practice, please visit https://oln-law.com/practice-areas/family-office-services/

i https://www.info.gov.hk/gia/general/202605/27/P2026052700809.htm

Filed Under: Family Office Sevices Tagged With: Family Office, Estate planning

  • Page 1
  • Page 2
  • Page 3
  • Interim pages omitted …
  • Page 55
  • Go to Next Page »

Primary Sidebar

This website uses cookies to optimise your experience and to collect information to customise content. By closing this banner, clicking a link or continuing to browse otherwise, you agree to the use of cookies. Please read the cookies section of our Privacy Policy to learn more. Learn more

Footer

OLN logo

Suite 503, 5/F, St. George's Building 2 Ice House Street, Central, Hong Kong

Tel. +852 2868 0696 | Email us
Chi Siamo Persone Sedi OLN IP Services Privacy Policy
Aree di Attività Insights Carriere OLN Online
About Practice Areas People Insights Offices
Careers OLN IP Services OLN Online Privacy Policy Home
linkedin twitter facebook
OLN logo

© 2026 Oldham, Li & Nie. All Rights Reserved.

Manage Consent
To provide the best experiences, we use technologies like cookies to store and/or access device information. Consenting to these technologies will allow us to process data such as browsing behavior or unique IDs on this site. Not consenting or withdrawing consent, may adversely affect certain features and functions.
Functional Sempre attivo
The technical storage or access is strictly necessary for the legitimate purpose of enabling the use of a specific service explicitly requested by the subscriber or user, or for the sole purpose of carrying out the transmission of a communication over an electronic communications network.
Preferences
The technical storage or access is necessary for the legitimate purpose of storing preferences that are not requested by the subscriber or user.
Statistics
The technical storage or access that is used exclusively for statistical purposes. The technical storage or access that is used exclusively for anonymous statistical purposes. Without a subpoena, voluntary compliance on the part of your Internet Service Provider, or additional records from a third party, information stored or retrieved for this purpose alone cannot usually be used to identify you.
Marketing
The technical storage or access is required to create user profiles to send advertising, or to track the user on a website or across several websites for similar marketing purposes.
  • Gestisci opzioni
  • Gestisci servizi
  • Gestisci {vendor_count} fornitori
  • Per saperne di più su questi scopi
View preferences
  • {title}
  • {title}
  • {title}
x